
Blogs
PW Consulting: Worldwide Elemental Fluorine Hits $928.5M in 2025, 6.18% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the 2026 Decision-Maker: Navigating the Worldwide Elemental Fluorine Market
In the landscape of specialized industrial chemicals, few commodities command as much strategic attention as elemental fluorine. As we transition from the historical baseline of 2025 into the forecast period spanning 2026 to 2032, organizations involved in the supply chain must recognize that this is not merely a commodity market but a critical enabler of advanced technologies. Our latest comprehensive study, the Worldwide Elemental Fluorine Market research, is designed to equip executive leadership with the foresight required to navigate this complex environment.
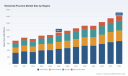
The market has demonstrated resilience and steady expansion over the past half-decade. Historical data from 2020 through 2025 indicates a compound annual growth trajectory that underscores the inelastic demand for high-purity fluorination agents. The overall market size, measured in millions of USD, has climbed from approximately 685.4 million in 2020 to an estimated 928.5 million in the base year of 2025. Looking forward, the forecast period projects a continuation of this momentum, with a CAGR of 6.18 percent. This growth is not linear; it is punctuated by supply chain constraints and regulatory shifts that require nuanced understanding. Our report deconstructs these trends to provide actionable intelligence rather than simple extrapolations.
Market Overview and Growth Trajectories
Understanding the macroeconomic flow of elemental fluorine is essential for capacity planning and investment strategy. The revenue stream has shown sensitivity to raw material costs, yet the demand side remains robust due to enduring requirements in semiconductor manufacturing and energy security sectors. The projected valuation for the market is expected to reach upwards of 1.4 billion USD by 2032. This expansion suggests that while volumetric growth is steady, the value capture opportunities differ significantly across application verticals and grade specifications.
Fluorine Gas (F2) Market
Strategic planners must note that growth rates vary when adjusting for inflation and feedstock volatility. The forecast period highlights 2026 as a pivotal year where pricing dynamics stabilize post-recent disruptions, only to face new pressures from upstream raw material constraints. The research details the correlation between anhydrous hydrogen fluoride costs and elemental fluorine pricing, providing a model for cost forecasting that accounts for fluorspar market fluctuations.
Segmentation Dynamics: Applications and Grades
The demand for elemental fluorine is bifurcated primarily by grade and application. Our analysis distinguishes between Industrial Grade and Electronic Grade specifications, each serving distinct value chains with different margin profiles. Electronic Grade fluorine, essential for high-precision semiconductor etching and cleaning, commands a premium due to stringent purity requirements. In contrast, Industrial Grade supplies broader chemical synthesis and nuclear fuel processing needs.
Application-wise, the market is driven by several key sectors. Uranium enrichment remains a cornerstone of demand, tied closely to national energy security policies and geopolitical stability. Simultaneously, the semiconductor manufacturing sector represents a high-growth vector, driven by the continuous shrinking of node sizes and the need for advanced fluorination processes in chip fabrication. Other significant applications include sulfur hexafluoride production for electrical insulation and the synthesis of fluorinated organic chemicals used in pharmaceuticals and agrochemicals.
The interplay between these segments creates opportunities for diversification. Companies that can bridge the gap between industrial bulk supply and high-purity electronic specifications often capture greater market share. Our report provides a detailed breakdown of volume splits and revenue contributions across these categories, allowing stakeholders to identify which verticals offer the highest return on investment relative to regulatory burdens.
Regional Geographic Insights
Geographically, the market is concentrated in specific hubs that align with both manufacturing capabilities and raw material availability. The Asia Pacific region stands as the largest consumption zone, reflecting the density of semiconductor fabs and chemical processing facilities in countries like Japan and broader East Asian markets. North America follows as a significant region, driven by domestic energy needs and a robust pharmaceutical sector. Europe maintains a steady presence, heavily influenced by regulatory frameworks such as REACH.
The Rest of the World segment includes key production sites in Africa and other mining-rich regions that feed the upstream supply chain. Our geographic analysis goes beyond simple consumption maps; it evaluates logistics corridors, trade barriers, and regional pricing differentials. For instance, the disparity in fluorspar production concentration between China and other regions creates arbitrage opportunities and supply risks that are meticulously mapped in the study. Understanding these regional inefficiencies is key to optimizing procurement strategies.
Competitive Landscape and Key Players
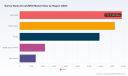
The market structure is characterized by high concentration, with the top three competitors holding a significant share of the global supply. The top five players command an even larger portion of the market, indicating a barrier to entry that protects established incumbents. This oligopolistic structure means that supply disruptions from a single major player can ripple through the global supply chain.
Key participants include Air Products and Chemicals, Inc., headquartered in Lehigh Valley, Pennsylvania. As a leading global supplier of ultra-high purity elemental fluorine gas, their focus on semiconductor etching and pharmaceutical synthesis positions them as a critical partner for high-tech industries. Solvay SA, based in Brussels, Belgium, produces elemental fluorine through electrolysis at facilities including the US. Their portfolio serves fluorochemical intermediates and nuclear fuel processing, though they have faced operational challenges such as force majeure declarations on hydrogen fluoride production following facility incidents.
Pelchem SOC Ltd, located in Pelindaba, South Africa, is recognized as the world's largest dedicated producer of elemental fluorine gas. They supply high-purity F2 for uranium enrichment and agrochemicals, making them a linestock for energy and agricultural security. In Asia, Kanto Denka Kogyo Co., Ltd. in Tokyo specializes in high-purity gas for electronics and solar cell manufacturing, while Stella Chemifa Corporation in Osaka manufactures fluorine compounds for semiconductor cleaning and lithium battery materials.
Recent developments highlight the volatility inherent in this competitive landscape. In 2022, Solvay declared force majeure on hydrogen fluoride production following a fire at their Green River, Wyoming facility, impacting downstream elemental fluorine supply. Conversely, in 2021, Pelchem SOC Ltd restarted full elemental fluorine production capacity after a scheduled maintenance shutdown. These events illustrate the fragility of the supply chain and the importance of monitoring operational status updates for key suppliers.
Supply Chain and Regulatory Risk Factors
Operationalizing elemental fluorine involves navigating a maze of regulatory and logistical hurdles. Elemental fluorine is classified as UN 1045, Poison Gas 2.3. This classification requires specialized UN-approved cylinders and strict adherence to DOT and EU ADR transport restrictions. Compliance is not optional; it is a fundamental constraint on logistics speed and cost. Furthermore, EU REACH authorization has been required for fluorine under Annex XIV since 2020, with ongoing reviews for industrial uses due to high reactivity and toxicity. These regulatory layers add time and cost to market entry and expansion plans.
Worldwide Elemental Fluorine Market
Raw material volatility presents another layer of risk. Acid-grade fluorspar prices averaged 289 per metric ton in 2023, up from 258 in 2022. This upward pressure directly impacts the cost of anhydrous hydrogen fluoride feedstock, which is the precursor for elemental fluorine production. In North America, anhydrous hydrogen fluoride spot prices rose to 2,800 per metric ton in the third quarter of 2023 amid fluorspar shortages. Additionally, China accounted for 64 percent of global fluorspar production in 2023, with export quotas tightened under Ministry of Commerce policies affecting HF and F2 supply chains. These factors create a volatile cost environment that must be hedged through strategic procurement.
Strategic Value of This Research
This report is not merely a collection of data points; it is a strategic tool designed for 2026 decision-making. It enables procurement directors to model cost scenarios based on fluorspar price volatility. It allows strategy officers to assess the risk exposure of relying on concentrated supply chains in specific regions. For R&D leaders, the segmentation analysis clarifies where purity demands are evolving, particularly in the electronics sector.
The inclusion of historical performance data from 2020 to 2025 provides a baseline for stress-testing current business models against past disruptions. The forecast period extends this utility, offering a window into future capacity requirements. By understanding the concentration ratios and the specific profiles of key competitors like Air Products and Pelchem, companies can better negotiate contracts and plan for contingencies.
Conclusion: Acquiring the Full Intelligence Picture
The Worldwide Elemental Fluorine Market is at a juncture where demand growth intersects with significant supply side constraints and regulatory complexity. The 6.18 percent CAGR projects a robust future, but realizing value in this market requires granular insight into who is producing what, where, and under what regulatory conditions.
The overview provided here scratches the surface of the available intelligence. To fully equip your organization for the challenges and opportunities of the 2026 to 2032 period, a detailed examination of the segmentation splits, regional revenue distributions, and specific competitive moves is necessary. We invite you to visit the source webpage to access the complete market research report. There, you will find the full dataset, including detailed regional and application segmentation breakdowns, comprehensive company profiles, and the proprietary models used to derive these strategic forecasts. Do not rely on approximations for such a critical input material; secure the detailed intelligence required to lead in the elemental fluorine market.
For detailed analysis of this topic, please visit the official page: Worldwide Elemental Fluorine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 9.5% CAGR for Global Medium Entropy Alloys Market in 2026-2032
By pmarketresearch, 2026-09-16
Strategic Radar: Navigating the Medium Entropy Alloys Market in 2026 and Beyond
Executive Overview
The materials science landscape is undergoing a profound transformation, driven by the demand for components that can withstand extreme environments while maintaining structural integrity. At the forefront of this shift is the Worldwide Medium Entropy Alloys Market. As industrial sectors push the boundaries of performance, medium entropy alloys have emerged as a critical solution, offering a balanced approach between the complexity of high entropy systems and the familiarity of traditional alloying methods. For strategic leaders operating in aerospace, defense, energy, and advanced manufacturing, understanding the trajectory of this market is no longer optional—it is a imperative for supply chain resilience and product innovation.
This analysis serves as an introduction to our latest comprehensive research publication. It highlights the macroeconomic signals, competitive tensions, and operational imperatives defining the sector. The goal is to equip decision-makers with the context needed to anticipate shifts in cost structures, technology adoption, and regional supply dynamics through the forecast period ending in 2032.
Market Trajectory and Growth Dynamics
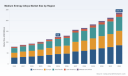
The economic footprint of medium entropy alloys has expanded steadily over the last half-decade, reflecting a transition from niche research applications to broader industrial implementation. Historical data indicates a consistent upward trend in market revenue, signaling robust adoption rates across key verticals. Starting from a baseline in the early 2020s, the market has demonstrated resilience despite broader economic fluctuations. By the base year of 2025, the sector achieved a significant revenue milestone, setting the stage for accelerated expansion in the coming years.
The forecast period projects a compelling growth CAGR, underscoring the increasing reliance on advanced material compositions for high-performance applications. This growth is not merely a function of volume but reflects a deepening integration of these alloys into critical infrastructure and next-generation technology platforms. Companies that recognize the timing of this expansion are better positioned to secure long-term supply agreements and invest in compatible manufacturing capabilities. The revenue trajectory suggests that the market will more than double in size by the early 2030s, representing a substantial value creation opportunity for stakeholders who can navigate the technical and logistical complexities involved.
Worldwide Medium Entropy Alloys Market
Segmentation and Demand Drivers
Understanding where demand originates is crucial for resource allocation. The market is naturally stratified by composition type, application sector, and geographic presence. While public high-level summaries provide a directional view, the detailed breakdown of these segments reveals specific pockets of intensity that drive overall market health.
- Alloy Composition Types: The landscape includes Cr-Co-Ni-based formulations, Fe-Cr-Ni-based systems, and other elemental compositions. Each type offers distinct mechanical properties and corrosion resistance profiles, catering to specific engineering requirements. The dominance of certain compositions often correlates with the maturity of processing technologies and the availability of upstream feedstocks.
- Application Verticals: Demand is heavily influenced by sectors requiring materials that perform under stress and heat. Aerospace and defense remain primary drivers, leveraging these alloys for structural components and engine parts. Automotive and transportation sectors are increasingly exploring these materials for lightweighting and durability. Energy and power generation applications utilize them for turbine blades and heat exchangers, while other industries adopt them for specialized tooling and medical devices.
- Regional Distribution: Consumption patterns vary significantly by region, influenced by local industrial bases, defense spending, and manufacturing capabilities. North America and Europe have historically held significant shares due to established aerospace and specialty metals industries. Meanwhile, Asia Pacific represents a dynamic growth zone, driven by manufacturing expansion and infrastructure development. Latin America and the Middle East and Africa contribute to the global mix, often tied to specific energy extraction and processing projects.
It is important to note that while these categories define the market structure, the specific revenue contributions and growth rates within each segment are subject to rapid change based on technological breakthroughs and supply chain constraints. Detailed segmentation data is contained within the full research report to ensure strategic accuracy.
Competitive Landscape and Key Players
The market is characterized by a mix of established specialty materials giants and agile innovators focused on computational design and additive manufacturing. The concentration of market share among top players indicates a competitive environment where differentiation is key.
Major Incumbents: Several large corporations hold significant positions in the supply chain. Carpenter Technology Corporation and ATI Inc. are prominent in the USA, offering advanced high-performance alloys for aerospace and energy sectors. Haynes International, Inc. specializes in nickel- and cobalt-based alloys, extending capabilities into medium entropy formulations for demanding environments. Sandvik AB, based in Sweden, develops advanced materials for aerospace and automotive sectors. VDM Metals GmbH in Germany manufactures nickel alloys and specialty materials applicable to these technologies.
Innovation and Supply Chain Enablers: Beyond traditional manufacturers, a layer of companies focuses on specific enabling technologies. QuesTek Innovations LLC emphasizes computational alloy design, accelerating development cycles. Hitachi Metals (Proterial Ltd.) in Japan produces specialty alloys for electronics and automotive uses. Additionally, suppliers like Matexcel, MSE Supplies, and Stanford Advanced Materials (SAM) play critical roles in providing alloy powders and machined products tailored for additive manufacturing and 3D printing, supporting the research and prototyping phases that precede mass production.
The competitive dynamic is not just about volume but about technical capability, intellectual property, and the ability to secure raw materials. Market concentration metrics suggest that a handful of players control a significant portion of the revenue, creating barriers to entry for new competitors while fostering partnerships between established firms and specialized innovators.
Strategic Risks and Industry Dynamics
While the growth outlook is positive, several structural factors introduce volatility and compliance costs that must be managed. Strategic planning requires a clear view of these external pressures.
- Raw Material Volatility: Production relies on upstream feedstocks such as nickel, cobalt, chromium, and titanium. Price volatility in these elements directly impacts alloy manufacturing costs. Fluctuations in commodity markets can erode margins or delay project timelines if hedging strategies are not in place.
- Geopolitical Supply Chain Risks: Sourcing of alloying elements like cobalt and nickel faces supply chain risks due to concentrated production in specific geographic regions. Geopolitical factors can disrupt flow, creating urgency for diversification of sourcing strategies and inventory buffering.
- Regulatory and Compliance Costs: Environmental regulations and material safety standards increase compliance costs for manufacturers. Processing and sourcing of critical elements are subject to stricter scrutiny, requiring investments in safer processing technologies and documentation.
- Sustainability Initiatives: There is a growing emphasis on reducing the carbon footprint of material production. The use of recycled stainless steel scrap and nickel alloy scrap reduces CO2 emissions compared to primary production in multicomponent alloy manufacturing. Companies integrating recycled feedstocks may gain competitive advantages in markets with strict sustainability mandates.
Operational Imperatives for 2026
As the market moves into the 2026 forecast period, several operational priorities emerge for industry participants.
1. Supply Chain Diversification: Given the geopolitical risks associated with critical elements, companies are advised to map their supply chains extensively. Relying on single-source suppliers for cobalt or nickel increases vulnerability. Strategic partnerships with multiple suppliers across different regions can mitigate disruption risks.
2. Investment in Additive Manufacturing: The availability of high-quality alloy powders from suppliers like Matexcel and MSE Supplies indicates a shift towards additive manufacturing. Industries should evaluate how medium entropy alloy powders can be integrated into 3D printing workflows to reduce waste and enable complex geometries that traditional machining cannot achieve.
3. Technology Adoption and R&D: Computational alloy design, as pioneered by firms like QuesTek, offers a pathway to faster development. Investing in digital tools that predict material properties can reduce the time-to-market for new alloy formulations. Collaboration between material scientists and computational experts is becoming a standard best practice.
4. Sustainability as a Competitive Edge: With compliance costs rising, leveraging recycled feedstocks where feasible can lower both environmental impact and potentially material costs. Demonstrating a commitment to sustainable practices can also enhance brand value among downstream customers in the automotive and aerospace sectors who have their own net-zero targets.
Conclusion: The Value of Deep Intelligence
The Worldwide Medium Entropy Alloys Market presents a landscape of significant opportunity tempered by complex operational challenges. The growth trajectory is strong, driven by essential demand from aerospace, defense, and energy sectors. However, realizing the potential of this market requires more than just observing top-line revenue figures. It demands a granular understanding of segmentation, competitive positioning, raw material dynamics, and regulatory shifts.
High-level data points, while useful for initial orientation, cannot capture the nuances required for precise strategic planning. Decisions regarding capacity expansion, M&A targets, or R&D focus require detailed segmentation data, region-specific forecasts, and deep dives into competitor strategies. The interplay between alloy compositions, application needs, and regional supply chains creates a matrix of variables that must be analyzed holistically.
Our full market research report provides this necessary depth. It moves beyond the macro overview to deliver actionable intelligence on market sizes, growth rates by segment, competitive share analysis, and strategic recommendations tailored to specific business objectives. For leaders preparing for the 2026-2032 horizon, accessing this granular intelligence is the critical next step in converting market potential into sustainable competitive advantage.
Shape Memory Alloys Market
For detailed analysis of this topic, please visit the official page: Worldwide Medium Entropy Alloys Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Umbilical Cable Market Hits $4.19B in 2025, Projected 7.1% CAGR to 2032
By pmarketresearch, 2026-09-16
Global Umbilical Cable Market 2026: Strategic Intelligence for Navigating Deepwater Expansion and Energy Transition
The subsea umbilical cable sector stands at a critical inflection point in 2026, driven by aggressive deepwater exploration, evolving flow assurance requirements, and parallel investments in offshore renewable infrastructure. As operators push development boundaries into ultra-deepwater frontiers and marginal fields require increasingly complex intervention systems, the umbilical value chain has transitioned from a commoditized supply segment to a highly engineered, performance-critical enabler of hydrocarbon and energy transition projects. PW Consulting newly released Worldwide Umbilical Cable Market research provides decision-makers with a structured, forward-looking intelligence framework designed specifically to support capital allocation, procurement strategy, and competitive positioning across the 2026 to 2032 horizon.
Worldwide Umbilical Cable Market
Subsea Umbilical Service Market
This strategic overview synthesizes historical performance, macroeconomic tailwinds, and the operational realities shaping global supply while deliberately reserving sector-specific quantification, regional breakdowns, and granular application analyses for the complete intelligence package. Enterprise leaders seeking to calibrate bidding strategies, evaluate supplier partnerships, and anticipate capacity constraints will find the full study structured to convert raw market signals into executable commercial roadmaps.
From Recovery to Sustained Growth: Mapping the Trajectory Through 2032
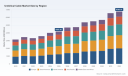
Historical data from 2020 through 2025 reveals a market that absorbed significant cyclical volatility before consolidating into a robust expansion phase. After navigating pandemic-era project deferrals, supply chain bottlenecks, and fluctuating crude price environments, the global umbilical cable market demonstrated notable resilience and rebounded with accelerated contract awards, renewed operator capex commitments, and expanded manufacturing throughput. By the base year of 2025, market revenue had firmly reestablished its growth trajectory, reflecting both the completion of previously delayed subsea projects and the early-stage awarding of next-generation deepwater and tie-back developments.
Forecasts extending through 2032 indicate that this momentum will not merely continue but structurally compound. The research models a compound annual growth rate of 7.1 percent across the entire global umbilical cable market, a trajectory that reflects sustained operator demand for high-specification umbilical systems capable of supporting longer tie-backs, higher pressure and temperature environments, and integrated power-communication-hydraulic architectures. Market size progression across the forecast window underscores an expanding addressable base as project complexity outpaces simple volume growth. Decision-makers evaluating this growth must recognize that it is not uniformly distributed across product categories, depth regimes, or geographies; rather, it is heavily concentrated in segments demanding advanced material science, rigorous testing protocols, and specialized installation expertise.
At the macroeconomic level, the market's absolute revenue scale signals a mature yet dynamically evolving industry where incremental innovation and strategic capacity investments directly influence competitive outcomes. The research dissects these growth vectors by isolating the underlying demand generators — from basin-level exploration patterns to utility-scale offshore energy deployments — without oversimplifying the nuanced factors that will determine which suppliers capture disproportionate value over the next seven years.
Segmentation Dynamics: Where Complexity Drives Commercial Differentiation
Umbilical cable markets do not move as monoliths. Performance requirements, regulatory environments, and operator preferences fracture demand across material architectures, operational depth classifications, and end-use applications, each carrying distinct engineering tolerances and commercial implications. The steel tube umbilical segment continues to anchor a substantial portion of market value, driven by its unmatched mechanical integrity, corrosion resistance, and suitability for high-pressure injection, chemical delivery, and long-life production systems in harsh subsea conditions. Complementary architectures, including thermoplastic hose umbilicals and specialized power umbilicals, serve distinct operational niches where flexibility, weight optimization, and electrical transmission requirements dictate design choices.
Depth classification further stratifies demand. Shallow water deployments, deepwater developments, and ultra-deepwater frontiers each impose fundamentally different stress profiles, installation methodologies, and lifecycle maintenance considerations. As operators increasingly target extended-reach tie-backs and frontier basins where flow assurance, thermal regulation, and reliable communication become non-negotiable, the commercial premium shifts toward suppliers capable of engineering integrated systems that address wax and hydrate mitigation, high-voltage power delivery, and fiber-optic telemetry within a single deployment architecture.
Application-side dynamics reveal parallel growth engines beyond traditional oil and gas production. Subsea intervention, ROV support, diving operations, seismic monitoring, defense applications, and expanding renewable energy arrays all require customized umbilical solutions tailored to dynamic loading, environmental exposure, and mission-critical reliability standards. The research maps these application intersections to identify which operational profiles are expanding fastest, where dual-use technologies are bridging subsea oil and gas with offshore wind and green hydrogen infrastructure, and how suppliers can repurpose engineering capabilities across adjacent markets without compromising specification integrity.
Competitive Architecture: Incumbents, Specialists, and Emerging Capacity Centers
The global umbilical cable competitive landscape reflects a hybrid structure: established multinational operators with integrated design, manufacturing, and subsea service capabilities coexist alongside specialized manufacturers and regional capacity hubs that concentrate on high-specification components, bespoke system integration, or localized project execution. Industry concentration metrics underscore the strategic importance of scale, certification depth, and proven project track records. The research details how leading suppliers leverage proprietary designs, dedicated manufacturing plants, and in-house testing infrastructure to maintain performance leadership, while mid-tier and regional players pursue differentiation through niche engineering expertise, rapid customization, and full-lifecycle support models.
Profiles of core market participants illustrate the breadth of strategic postures shaping 2026 competition:
- Global technology-driven subsea solution providers anchor the upper tier through integrated steel tube, thermoplastic hose, and hybrid umbilical engineering, supported by multi-continent manufacturing footprints and deep project delivery experience across oil and gas basins.
- Specialized subsea contractors and cable system manufacturers emphasize complete umbilical architectures for deepwater and harsh environments, combining power, control, and communication distribution with extensive installation support capabilities and expanding portfolios that address renewable energy array and export cable requirements.
- Integrated subsea technology units within larger industrial portfolios focus on robust umbilical systems for ultra-deep water, pairing patented mechanical and electrical designs with integrated production control, chemical injection, and flow assurance functionality tailored to extreme depth and pressure conditions.
- Long-tenured subsea cable specialists with decades of offshore project experience concentrate on high-pressure, high-temperature, long tie-back applications, frequently aligning with national oil company agendas and major operator specifications where proven reliability and regional project familiarity drive contract selection.
- Global suppliers of subsea control umbilicals, power cables, and hybrid systems provide end-to-end design, manufacture, testing, and offshore installation services, with recent project activity spanning Middle East gas infrastructure, offshore platform cable testing, and deployment monitoring support.
- Bespoke static and dynamic umbilical specialists deliver customized cable, hose, and termination solutions for demanding subsea environments, maintaining in-house design, testing, and project management capabilities that emphasize mission-specific performance under dynamic loading and corrosive conditions.
- Complex custom cable and specialty umbilical manufacturers serve subsea oil and gas, diving, ROV, seismic, defense, and renewable applications, emphasizing engineered flexibility for dynamic harsh environments and integrated system delivery.
- Global manufacturers meeting stringent industrial and subsea design criteria contribute specialized umbilical cable production capacity, reinforcing supply diversification for complex specification requirements.
- Composite subsea umbilical cable producers operating across UK and Brazilian manufacturing partnerships deliver electro-hydraulic, injection, optical, and power umbilicals engineered for offshore oil and gas deployments to significant depths, reflecting the strategic importance of regional production synergies.
- Asian cable manufacturers expand marine oil and gas exploration cable portfolios, including umbilical, optical, electrical, and composite cable solutions, positioning themselves along the supply chain for growing subsea project volumes.
- Submarine cable enterprises engaged in R and D, design, and production for marine resource development increasingly intersect with umbilical cable manufacturing as offshore energy and resource extraction projects expand their subsea interface requirements.
- Specialty stainless steel tube suppliers occupy a critical upstream position in the steel tube umbilical value chain, delivering seamless tubing that directly influences tensile strength, corrosion resistance, and deepwater performance for high-specification umbilical assemblies.
Recent operational developments reinforce how individual supplier activities translate into broader market signals. Tubacex's early 2026 securing of three new umbilical tube contracts aggregating to a combined €26 million across the Gulf of Mexico, Brazil, Mediterranean, Australia, and Africa illustrates sustained demand for specialized stainless steel tubing and record offshore segment order books. JDR Cable Systems' 2025 contract award to test 14 umbilical cables for offshore platforms in the Middle East, encompassing pre-deployment testing, lay operation monitoring, and integration support, highlights the growing commercial weight of quality assurance, lifecycle testing, and integration services alongside physical manufacturing. Meanwhile, the 2025 Umbilicals Conference convened by the Umbilical Manufacturers' Federation and Global Underwater Hub brought manufacturers, designers, installers, and operators together to align on subsea umbilical advancements, signaling continued industry-wide focus on standardization, technological progression, and cross-value-chain collaboration.
Technology, Materials, and Regulatory Forces Reshaping Procurement Decisions
Subsea umbilical systems perform indispensable functions that extend far beyond simple fluid or power transport. Modern architectures integrate hydraulic and chemical injection capabilities, electrical power delivery, fiber-optic communication pathways, and active flow assurance mechanisms including heating solutions that prevent wax and hydrate formation in ultra-deepwater developments. As fields extend in distance, depth, and operating temperature, umbilical design assumptions must accommodate longer deployment lengths, higher pressure containment thresholds, greater dynamic movement exposure, and increased reliability expectations over extended production lifecycles.
Raw material engineering directly shapes competitive differentiation. Stainless steel and super duplex tubes remain foundational components for steel tube umbilicals, providing the high tensile strength and corrosion resistance required for deepwater and high-pressure applications. Supplier capability in seamless tube production, metallurgical quality control, and precision manufacturing determines whether system designers can meet increasingly aggressive performance specifications without compromising manufacturability or cost structures. The sustained demand for these specialized materials, as evidenced by recent contract awards and elevated order book levels, confirms that material-grade capabilities are becoming decisive competitive differentiators rather than routine commodity inputs.
Regulatory and quality assurance expectations further intensify as installation and long-term operation in harsh subsea environments demand strict compliance with offshore safety, performance, and certification standards. Procurement teams increasingly evaluate not only initial unit economics but also testing rigor, deployment monitoring support, warranty structures, and the supplier's demonstrated capacity to sustain performance across the full project lifecycle. Industry investments in R and D facilities and expanded manufacturing capacity for longer, higher-specification umbilicals indicate that competitive positioning will increasingly hinge on engineering depth, testing infrastructure, and the ability to deliver integrated solutions that satisfy both operator technical requirements and regulatory compliance mandates.
Strategic Utility: Translating Market Intelligence into 2026 Decision Advantage
For corporate strategy teams, procurement leaders, and investment analysts, the Worldwide Umbilical Cable Market research delivers an operational intelligence architecture designed to convert market complexity into structured decision support. The study integrates historical performance analysis, forward-looking growth modeling, segmentation mapping, competitive profiling, and material and technology trend assessment into a unified analytical framework that directly informs bidding strategy, supplier selection, partnership evaluation, and capacity planning.
Rather than presenting static market snapshots, the research prioritizes actionable segmentation logic and comparative supplier positioning so that readers can identify where value is concentrating, which technical capabilities are becoming table stakes, and how regional manufacturing footprints intersect with project geography and operator preference. By aligning macroeconomic growth indicators with granular supply-side dynamics, the report equips enterprises to anticipate shifts in bidding intensity, assess where specialized testing and integration services add negotiating leverage, and evaluate which competitors are most likely to secure advantage in high-specification deepwater and ultra-deepwater assignments.
The analysis is deliberately designed to support scenario-based planning. Readers can use the segmentation structures to stress-test exposure across product categories and depth regimes, evaluate supplier concentration risk against procurement requirements, and align internal engineering roadmaps with the market's accelerating demand for integrated power, control, chemical injection, and flow assurance solutions. For organizations assessing market entry, capacity expansion, or partnership opportunities, the report provides the contextual scaffolding necessary to evaluate fit without overcommitting to unsubstantiated assumptions about regional or application-specific value distribution.
A complete review of the 2026 to 2032 forecast architecture, segmentation splits, competitive positioning matrices, and detailed regional and application-level intelligence is available through the full publication. The research has been structured to ensure that each section translates directly into decision-ready insight, enabling executive teams, sales leadership, and strategic planning functions to move from observation to execution with confidence. For those responsible for navigating subsea capital programs, supplier negotiations, and long-term portfolio strategy, the complete Worldwide Umbilical Cable Market study offers the structured intelligence needed to act decisively in a market where performance, reliability, and engineering differentiation increasingly define commercial winners.
For detailed analysis of this topic, please visit the official page: Worldwide Umbilical Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Narrow Body Aircraft MRO Market to Hit $55.24B in 2025, CAGR 5.6% Through 2032
By pmarketresearch, 2026-09-16
Navigating the Narrow-Body MRO Landscape: Strategic Intelligence for 2026 and Beyond
The global maintenance, repair, and overhaul (MRO) sector for narrow-body aircraft is entering a decisive phase. As airlines accelerate fleet renewals and optimize legacy operations, the narrow-body segment has emerged as the primary engine of MRO revenue growth. PW Consulting is pleased to introduce our Worldwide Narrow Body Aircraft MRO Market report, a comprehensive strategic resource designed to equip executives, investors, and MRO operators with the forward-looking intelligence required to navigate the 2026–2032 forecast period. This publication moves beyond headline figures to deliver an operational blueprint for capacity planning, competitive positioning, and risk mitigation in one of aviation’s most dynamic segments.
The market has demonstrated remarkable resilience and expansion over the past half-decade. Valued at approximately 32,450 million USD in the base year of 2020, the sector climbed steadily through the post-pandemic recovery, reaching an estimated 55,241 million USD by 2025. The trajectory forward underscores sustained momentum, with the market projected to expand at a compound annual growth rate of 5.6 percent. By 2032, the narrow-body MRO market is expected to surpass 80,893 million USD. These figures reflect deeper structural shifts: the replacement of aging fleets with fuel-efficient narrow-body platforms, the compounding effect of recurring maintenance cycles, and the increasing complexity of engine and component overhauls. Our report translates these macro-level indicators into actionable scenarios, enabling decision-makers to align capital allocation, facility investments, and service portfolio strategies with measurable market realities.
Decoding the Competitive Architecture
The narrow-body MRO landscape is characterized by a mix of integrated airline-affiliated shops, globally scaled independent providers, and highly specialized regional players. Our analysis maps the strategic positioning of leading enterprises that are actively shaping capacity, certification pathways, and service breadth across key operating theaters. Lufthansa Technik continues to leverage its multi-facility network across Europe, delivering base and line maintenance alongside engine overhaul capabilities for both CFM56 and LEAP powerplants across the Airbus A320 family and Boeing 737 series. ST Engineering Aerospace maintains its status as the world’s largest independent airframe MRO provider by man-hours, offering nose-to-tail services with a particularly strong footprint in the Asia-Pacific region and expanding capabilities in the United States and Europe. AAR Corp. reinforces its leadership in North America through dedicated narrow-body facilities and recent capacity expansions in Oklahoma City and Miami, focusing on airframe, component repair, and landing gear overhaul for 737 and A320 platforms.
Worldwide Narrow Body Aircraft MRO Market
Airline-affiliated models remain highly influential. Delta TechOps has established a differentiated position in North America by securing full licensed overhaul capability for both CFM LEAP-1A and LEAP-1B engines, complemented by extensive hangar capacity tailored to narrow-body fleets. SR Technics concentrates on engine heavy shop visits and component MRO, supported by long-term maintenance agreements that underscore the enduring demand for CFM56-7B services among Boeing 737NG operators. In Asia, HAECO delivers integrated airframe, line, and component support for narrow-body platforms, including dedicated operations for the A321neo and regional joint ventures optimized for short-haul networks. Turkish Technic has scaled its throughput significantly through large multi-hangar facilities capable of servicing up to 26 narrow-body aircraft simultaneously, while Iberia Maintenance and TAP Maintenance & Engineering anchor European capacity with specialized engine overhaul programs covering V2500 and GTF architectures alongside component and airframe services.
Recent operational milestones from these organizations illustrate how strategic execution is translating into market advantage. In early 2026, SR Technics formalized a multi-year agreement with a major North American carrier for CFM56-7B heavy shop visit maintenance, reinforcing the persistent demand for legacy engine support. During the same period, Delta TechOps achieved full licensed overhaul qualification for both LEAP-1A and LEAP-1B engines, positioning the provider as the sole North American airline-affiliated MRO with this dual-certification capability. The broader ecosystem has also seen substantial commitments: a memorandum of understanding between Ryanair and CFM International outlines long-term material services covering roughly 2,000 CFM56 and LEAP engines across the carrier’s Boeing 737 fleet. Meanwhile, facility expansions continue to reshape regional capacity. ST Engineering opened a new engine MRO facility in Singapore designed to double throughput for CFM56 and LEAP maintenance, targeting more than 300 annual shop visits by 2027. HAECO commenced line maintenance support for Cathay Pacific’s A321neo operations at Hong Kong International Airport, establishing the carrier as its largest narrow-body customer by flight volume. These developments are not isolated events; they signal a coordinated push toward higher certification coverage, geographic diversification, and specialized engine service readiness.
Core Structural Dynamics Shaping Service Delivery
Several interlocking forces are redefining how narrow-body MRO services are priced, scheduled, and delivered. Fleet composition remains the foundational driver. Narrow-body aircraft dominate global civil MRO demand because of their extensive deployment on short-haul and high-frequency routes, generating predictable but intensifying maintenance cycles across the Airbus A320 and Boeing 737 families. As operators pursue fuel efficiency and range improvements, next-generation platforms are entering service while mature and regional narrow-body fleets continue to require ongoing support. This dual pressure expands the service envelope and complicates shop scheduling, particularly when heavy maintenance intervals converge with engine performance restoration requirements.
Regulatory and certification requirements add a further layer of complexity. The CFM International LEAP engine family, which powers both the A320neo and 737 MAX, relies on specialized Premier MRO licensing and structured performance restoration shop visits. Providers are actively expanding certified capabilities to match fleet growth, and the competitive advantage increasingly belongs to organizations that can demonstrate full-scope authorization, disciplined quality management, and rapid turnaround on high-demand powerplants. Simultaneously, supply chain bottlenecks persist. Parts availability constraints and production delays for both aircraft and engines have extended MRO turnaround times and elevated costs across the industry. These disruptions are not merely operational inconveniences; they influence slot utilization, revenue forecasting, and the economics of outsourcing versus in-sourcing maintenance activities.
Cost dynamics remain a central concern for operators and MRO providers alike. The sector continues to face persistent shortages of certified mechanics, which have contributed to wage inflation of approximately 6.6 percent in 2024 with projections near 5.7 percent for 2025. These labor pressures directly affect turnaround times and the cost base of narrow-body maintenance programs. Material costs have followed a similar trajectory, rising by an average of 7.7 percent in 2024, exceeding earlier expectations of 6.5 percent, with 2025 projections estimated around 6.3 percent. The combination of skilled labor scarcity and elevated input prices is reshaping margin structures and compelling providers to invest in productivity improvements, digital scheduling tools, and more resilient supplier networks. Our report isolates these pressures, analyzes their differential impact across MRO activity lines, and identifies operational levers that can protect margins without compromising service quality.
What the Report Delivers: A Practical Intelligence Framework
This study is structured to support immediate and medium-term decision-making across multiple functional domains. Rather than offering a static snapshot, the report provides a layered analytical environment that integrates historical performance trends, forward-looking demand drivers, and competitive benchmarking into a coherent framework. Readers will gain access to detailed assessments of MRO activity segmentation, aircraft generation mix, and regional service distribution, all contextualized within the broader operational realities of fleet turnover, regulatory certification, and supply chain resilience.
- Comprehensive market sizing and growth trajectory analysis spanning historical baseline data and a multi-year forecast, enabling scenario planning for capacity expansion, pricing strategy, and service portfolio optimization.
- Granular segmentation analysis across MRO activity categories—including engine maintenance, airframe maintenance, component maintenance, and line maintenance—showing how revenue concentration shifts as maintenance cycles, engine shop visit frequencies, and component replacement patterns evolve.
- Aircraft generation segmentation that distinguishes between current-generation platforms, next-generation narrow-body introductions, and mature or regional narrow-body fleets, helping operators anticipate differing maintenance intensities and lifecycle service requirements.
- Regional distribution insights that map where maintenance demand is concentrated, how provider networks are scaling to capture share, and which geographic markets present the most favorable operational economics for base, line, and component services.
- Competitive landscape profiling that combines company headquarters, service scope, facility footprints, and recent capability expansions into a comparative view of market positioning and strategic direction.
- Structural dynamics assessment covering labor cost inflation, material cost trends, certification requirements, and supply chain pressures, with implications for turnaround times, margin management, and long-term sourcing strategies.
- Recent developments tracking that integrates contract awards, facility openings, capability certifications, and long-term service agreements to highlight the pace and direction of market activity.
The report also examines market concentration characteristics to clarify how competitive share is distributed among leading providers and what this implies for pricing power, partnership opportunities, and barriers to entry. By connecting these structural insights with real-world developments—such as dual LEAP engine certification achievements, multi-year heavy shop visit agreements, and targeted capacity expansions—the study helps readers distinguish temporary disruptions from durable market shifts. Each section is designed to be referenced independently or read as a continuous narrative, depending on whether the priority is market entry evaluation, outsourcing strategy refinement, capacity planning, or investment due diligence.
Strategic Imperatives for 2026 Decision-Makers
For executives operating in or adjacent to the narrow-body MRO ecosystem, the 2026 outlook demands a disciplined balance between growth ambition and operational realism. The projected mid-single-digit compound annual growth rate signals sustained demand, but the underlying composition of that demand is shifting. Engine maintenance remains the largest activity category, reflecting the durability requirements of modern narrow-body powerplants and the extended service life of in-service fleets. Airframe and component maintenance continue to represent substantial revenue streams, while line maintenance supports the high-frequency operational tempo that defines short-haul networks. Providers that align facility throughput, certification coverage, and spare parts logistics with these activity-specific demand patterns will be better positioned to capture share without overextending capital.
Geographic diversification is equally important. The regional distribution of narrow-body MRO demand highlights where operator networks are densest, where fleet renewal activity is most active, and where provider competition is intensifying. Airlines and independent MRO organizations alike must evaluate whether existing footprints can absorb incoming maintenance volume, whether partnership or joint-venture structures can accelerate market access, and whether localized sourcing strategies can mitigate the cost and delay implications of extended supply chains. The concentration of competitive activity among a core group of established providers suggests that differentiation will increasingly depend on certification breadth, turnaround reliability, and the ability to manage labor and material cost pressures without eroding service standards.
Operational resilience will separate sustainable performers from those that merely capture short-term volume. Skilled labor availability, wage trends, and the cost of components and raw materials are not isolated line items; they are systemic variables that influence scheduling confidence, contract profitability, and customer retention. Organizations that invest in workforce development, digital maintenance planning, and supplier diversification can convert these challenges into competitive advantages. Similarly, providers that anticipate the next wave of engine shop visit demand—especially for LEAP platforms and high-utilization CFM56 fleets—can secure long-term service agreements and optimize hangar utilization ahead of tighter capacity windows.
Aircraft Engine MRO Market
The strategic questions facing the market are clear. Which regional markets offer the most favorable balance of demand growth and operational cost? How should organizations sequence facility investments to match forecast maintenance cycles without creating idle capacity? What certification pathways are becoming essential as engine architectures and regulatory expectations evolve? How can operators and providers structure partnerships that balance risk, share capability, and improve responsiveness to supply chain volatility? The Worldwide Narrow Body Aircraft MRO Market report is built to answer these questions with precision, drawing on rigorous market sizing, segmentation analysis, competitive profiling, and forward-looking scenario modeling.
Accessing the Full Intelligence Package
This article provides a strategic preview of the market environment and the analytical depth contained within our latest study. The complete report expands on every dimension introduced here, delivering the detailed segmentation data, regional breakdowns, activity-level revenue distributions, aircraft-generation analyses, and competitive benchmarking required for confident decision-making. We invite airline executives, MRO operators, investors, and aerospace supply chain leaders to access the full publication for comprehensive market intelligence, scenario-based forecasts, and operational recommendations tailored to the narrow-body segment. As the 2026–2032 cycle unfolds, those who align strategy with granular, validated market insight will be best equipped to capture durable value in a market defined by both opportunity and complexity.
For detailed analysis of this topic, please visit the official page: Worldwide Narrow Body Aircraft MRO Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Biometric Signature Pads Market to Reach $778.31M by 2032, 7.15% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Biometric Signature Pads Market Understanding Growth Vectors and Competitive Dynamics Through 2032
The modern enterprise operates at the intersection of operational efficiency and stringent regulatory compliance. Nowhere is this tension more palpable than in the digitization of authentication and authorization workflows. The Biometric Signature Pads Market represents a critical hardware frontier in this transition, evolving from simple digital capture devices to sophisticated security nodes that integrate biometric verification, encryption, and legally binding eSignature protocols. Our latest research initiative provides a comprehensive longitudinal analysis of this sector, offering decision-makers the clarity required to navigate the forecast period from 2026 through 2032.
This market intelligence is not merely a compilation of historical figures; it is a strategic tool designed to inform capital allocation, supply chain resilience, and product development roadmaps. By understanding the trajectory of hardware adoption and the shifting regulatory landscape, organizations can secure a competitive advantage in a sector defined by both technological innovation and legal necessity.
Historical Trajectory and 2032 Projections
Over the past half-decade, the market has demonstrated consistent expansion, driven by the global shift away from paper-based processes. Our analysis tracks revenue performance from 2020 through the base year of 2025, establishing a robust baseline for future modeling. The data indicates a steady climb in market valuation, moving from approximately 345.5 million USD in 2020 to an estimated 480.0 million USD by 2025. This growth reflects the accelerating adoption of electronic signature solutions across both public and private sectors during a period of significant digital transformation.
Biometric Signature Pads Market
Looking forward, the forecast period projects continued momentum, with the market expected to reach nearly 497.98 million USD in 2026 and further climbing toward the 778 million USD mark by 2032. This trajectory implies a healthy compound annual growth rate over the forecast window, signaling sustained demand despite broader economic fluctuations. For strategic planners, these figures suggest that investment in biometric signature hardware is not a transient trend but a structural shift in how business agreements are executed and secured. The longevity of this growth curve underscores the importance of integrating these technologies into long-term IT infrastructure strategies rather than treating them as short-term compliance fixes.
Regulatory Dynamics and Compliance Imperatives
The evolution of the market is inextricably linked to the regulatory environment. In the European Union, the eIDAS Regulation (910/2014) sets a high bar for electronic identification and trust services. Biometric signature pads play a pivotal role here, supporting advanced electronic signatures by capturing dynamic biometric data such as pressure levels and signing speed. These data points are compliant with ISO/IEC 19794-7:2014 standards, ensuring legal validity across member states. For organizations operating within or trading with the EU, hardware that fails to meet these specifications exposes the enterprise to significant legal risk.
Furthermore, signature pads must meet rigorous security requirements to function as qualified signature creation devices under eIDAS. This grants the highest level of legal equivalence to handwritten signatures within the EU framework. Consequently, procurement decisions are no longer solely about cost or durability; they are about liability management. The ability of a device to produce a signature that holds up in court or during audit processes is a primary driver of premium hardware adoption. This regulatory pressure creates a moat around high-security devices, favoring vendors that invest heavily in encryption and compliance certification.
Technology Segmentation and Functional Demand
While the market is unified by the core function of capturing signatures, the underlying technologies vary significantly in their capabilities and use cases. The landscape is dominated by LCD signature pads, which offer visual verification for the signer, ensuring non-repudiation. These devices remain the standard for high-value transactions where visual confirmation is critical. However, the integration of biometric sensors represents a key differentiator. Fingerprint-integrated pads add a layer of identity verification, linking the signature event to a specific physiological trait. This dual-factor approach is becoming increasingly relevant in sectors where identity fraud is a high risk.
Signature Pad Market
Conversely, passive or pen-only pads serve cost-sensitive segments where high-end biometric features are not required. Understanding the distribution of demand across these technology types is essential for manufacturers and channel partners. Some sectors prioritize the visual interface and legal compliance features of LCD models, while others may opt for the durability and simplicity of capacitive pen-based solutions. The report delineates these technology paths without oversimplifying them, allowing stakeholders to identify which technical specifications align with their specific risk profiles and user experience requirements.
Competitive Landscape and Key Player Strategies
The market features a diverse array of global players, each with distinct strategic positioning. Topaz Systems, based in Simi Valley, California, offers a wide range of electronic and biometric signature pads including LCD models with fingerprint sensors. Their focus on healthcare, legal, and financial sectors highlights a strategy centered on vertical-specific compliance and reliability. Similarly, Scriptel Corporation in Columbus, Ohio, provides durable capacitive pen-based ScripTouch LCD and non-LCD electronic signature pads optimized for high-volume use. Their integration with healthcare systems like Epic indicates a strategic move to embed their hardware within critical medical workflows.
On the international stage, Wacom Co., Ltd. in Japan manufactures the STU series biometric signature pads that capture dynamic data including pressure levels. Their reputation in input devices lends significant credibility to their security claims. ePadLink (Interlink Electronics) supplies the ePad family of electronic signature pads with IntegriSign software, emphasizing secure, legally binding eSignatures across business applications. This software-hardware integration strategy aims to streamline the user experience while maintaining legal robustness.
European manufacturers are particularly strong in this space, driven by the immediate need to comply with regional regulations. StepOver GmbH in Germany develops the duraSign series, featuring color displays and high-security encryption with eIDAS compliance. Notably, in December 2025, StepOver launched the duraSign Pad 5.0, a robust 5-inch color display signature pad with tempered glass and USB-C connectivity. This product launch underscores the industry trend toward higher durability and modern connectivity standards to support continuous use in demanding environments. Euronovate Group, operating out of Switzerland and Italy, specializes in EnSign biometric graphometric signature pads with NFC options and multi-touch capabilities. Signotec GmbH, also based in Germany, produces high-security signature pads with biometric capture and eIDAS organization seals, focusing on ISO-compliant solutions for professional electronic signatures.
The competitive dynamics reveal a market where consolidation of supply chains and compliance certifications are becoming as important as hardware specifications. With market concentration indicating that top players hold a significant share of the revenue, new entrants or expanding competitors must differentiate through specialized features or regional compliance expertise to gain traction.
Strategic Considerations for 2026 and Beyond
As we move into 2026, several macro-level factors will influence the market trajectory. Supply chain resilience remains a critical concern. US electronics imports, including components for signature pads, face baseline tariffs impacting costs for manufacturers reliant on global supply chains from Asia. This trade policy environment necessitates a careful evaluation of sourcing strategies. Companies must weigh the cost benefits of overseas manufacturing against the risks of tariff fluctuations and logistical delays. The report provides a detailed assessment of how these trade dynamics might affect unit economics and pricing strategies for the forecast period.
Additionally, the concentration of market revenue among top firms suggests that partnership ecosystems are vital. With the top three and top five firms commanding a substantial portion of the market, smaller organizations may need to align with established vendors to ensure longevity and support. The report analyzes these concentration metrics to help buyers assess vendor risk and stability.
For technology procurement leaders, the strategic value of this research lies in its ability to connect high-level market trends with actionable decision criteria. It moves beyond simple demand forecasting to explore the why and how of adoption. Are you investing in LCD technology for visual assurance, or biometric integration for identity security? Is your primary driver eIDAS compliance for European markets, or general eSignature efficiency for domestic operations? The answers to these questions determine which segment of the market you should target and which vendor profiles align with your risk tolerance.
Conclusion and Access to Deep-Dive Intelligence
The Biometric Signature Pads Market is poised for sustained growth, underpinned by regulatory mandates, technological advancement, and the ongoing digitization of global commerce. However, capturing value in this market requires more than a surface-level understanding of growth rates. It demands a nuanced grasp of technological segmentation, competitive maneuvering, and the regulatory frameworks that define legal validity. Our full market research report offers this depth.
We invite industry leaders, investors, and strategic planners to access the complete intelligence suite. The full report contains detailed breakdowns of regional performance, specific application sector valuations, and granular competitor profiling that goes beyond the summary provided here. In a landscape where compliance and security are paramount, having access to precise, data-backed intelligence is the difference between reactive procurement and proactive strategic positioning. Secure your copy to leverage the full spectrum of insights derived from our comprehensive analysis of this evolving market.
For detailed analysis of this topic, please visit the official page: Biometric Signature Pads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 2025 Insulinoma Market Hits $166.8M, Projected 5.75% CAGR Through 2032
By pmarketresearch, 2026-09-16
Navigating the Global Insulinoma Market: Strategic Imperatives for 2026 and Beyond
Market Trajectory and Core Structural Shifts
The global insulinoma landscape is entering a decisive phase of structural recalibration, driven by converging forces in clinical innovation, regulatory alignment, and shifting treatment paradigms. Over the historical window of 2020 through 2025, the worldwide insulinoma market expanded from approximately 126.12 million USD to 166.8 million USD, reflecting a compound trajectory shaped by growing diagnostic precision, refined surgical protocols, and incremental pharmacological adoption. Looking ahead to the forecast period spanning 2026 through 2032, the market is projected to continue its measured expansion, anchored by a compound annual growth rate of 5.75 percent and culminating in a total valuation of roughly 246.68 million USD by 2032. These macro-level indicators frame a sector that is simultaneously niche and clinically critical, offering strategic decision-makers a clear window into capital allocation, pipeline prioritization, and go-to-market execution during a period of accelerating therapeutic innovation.
The quantitative progression from 134.11 million USD in 2021 to 162.18 million USD in 2024 underscores an inflection point where clinical research activity, specialized care infrastructure, and targeted investment began converging at practical levels. That momentum carried forward into 2025 and is expected to sustain through 2026, with the market settling around 168.35 million USD before accelerating into the 191.62 million USD range by 2027. For healthcare strategists, pharmaceutical planners, and medical technology executives, this pattern is not merely a financial artifact. It represents a structural narrative: insulinoma management is transitioning from a predominantly surgical and symptomatic intervention model toward an ecosystem where biologic therapies, precision diagnostics, and specialized care pathways increasingly intersect.
Segmentation Dynamics and Operational Realities
Behind the aggregate market figures lies a highly stratified operational environment that demands rigorous segmentation awareness for any enterprise operating within endocrinology, oncology support, or advanced medical devices. The worldwide insulinoma market is organized across multiple interdependent dimensions, each carrying distinct commercial implications, adoption velocities, and operational constraints. Treatment type architectures continue to reflect established clinical hierarchies while simultaneously absorbing emerging modalities, and end-user configurations reveal how care delivery is being reorganized around specialized centers, hospital networks, and diagnostic and research institutions. Regional distributions similarly illustrate how infrastructure maturity, reimbursement frameworks, and clinical trial accessibility influence market penetration patterns.
What makes this segmentation landscape particularly consequential for strategic planning is the uneven pace of innovation across categories. Surgical procedures remain the foundational intervention for localized disease, but the growing recognition of refractory and metastatic subtypes is reshaping how clinicians, investors, and manufacturers position complementary modalities. Pharmacological management, peptide-based approaches, and targeted biologic candidates are steadily expanding the therapeutic arsenal, particularly for patients who cannot undergo resection or who experience persistent hypoglycemia despite conventional management. End-user dynamics further reflect a shift toward institutional specialization, where hospitals continue to function as central treatment nodes, specialty clinics manage complex follow-up pathways, and diagnostic and research centers play an increasingly vital role in case identification, trial recruitment, and biomarker validation.
For corporate strategists, the critical insight is that segmentation performance cannot be interpreted in isolation. Market share, pricing architecture, reimbursement positioning, and clinical adoption are tightly coupled, and misjudging any one dimension can compromise product launch sequencing, partnership selection, and regional prioritization. This is why advanced market intelligence must move beyond headline valuations and examine the structural mechanics that govern how demand materializes across care settings, how value is distributed among treatment modalities, and how regional ecosystems influence time-to-adoption for novel interventions.
Competitive Landscape and the Emerging Therapeutic Frontier
The current competitive environment in the worldwide insulinoma market is characterized by a high degree of clinical concentration, enabling a relatively small cohort of organizations to shape downstream innovation, reimbursement discourse, and physician adoption pathways. Market concentration metrics indicate that a core subset of participants accounts for a disproportionately large share of commercial activity, while broader ecosystem players are increasingly focused on modality-specific innovation, partnership-led development, and precision medicine positioning. This concentration has important strategic implications. It means that competitive intelligence must account not only for revenue footprint but also for intellectual property cadence, clinical trial design, regulatory engagement, and the ability to align with unmet clinical needs in refractory disease populations.
Rezolute, Inc., headquartered in Redwood City, California, exemplifies the type of focused biopharmaceutical entrant that is actively reshaping therapeutic expectations within the rare endocrine oncology space. The company is advancing ersodetug (RZ358), an anti-insulin monoclonal antibody designed for tumor-mediated hyperinsulinism, including malignant insulinoma and refractory hypoglycemia. Its development trajectory has become a central reference point for stakeholders evaluating how biologic interventions might complement or extend beyond current surgical and pharmacological standards.
Recent regulatory developments have elevated the strategic significance of this pipeline. In September 2025, the company announced FDA alignment on a streamlined single-arm, open-label Phase 3 upLIFT trial design for ersodetug in approximately 16 patients with tumor hyperinsulinism. Topline data are expected in the second half of 2026, positioning the trial timeline directly within the early window of this forecast period and making it a closely watched catalyst for both clinical practice and commercial planning. Importantly, regulatory alignment also confirms that positive results from the pivotal sunRIZE Phase 3 trial in congenital hyperinsulinism can serve as supportive or confirmatory evidence for the tumor hyperinsulinism indication. This cross-indication evidentiary strategy could materially influence how development risk, regulatory pathway feasibility, and clinical adoption scenarios are modeled by investors and R&D teams.
From a competitive strategy perspective, these developments illustrate a broader pattern: insulinoma-related innovation is increasingly leveraging rare-disease development efficiency, regulatory consultation, and indication expansion logic. Companies operating in adjacent endocrinology, hypoglycemia management, or oncology-support arenas must therefore monitor not only direct competitors but also clinical trial milestones, regulatory design nuances, and evidence-generation strategies that could redefine treatment standards. The ability to anticipate such shifts is especially valuable in a market where patient populations are limited, clinical adoption depends heavily on specialized expertise, and commercial success is closely tied to reimbursement narratives and physician confidence in novel mechanisms of action.
Epidemiology, Patient Access, and Strategic Positioning
Any credible strategic assessment of the worldwide insulinoma market must account for the epidemiological and clinical constraints that define the addressable opportunity. Insulinomas are estimated to occur at an incidence of roughly one to four cases per million persons per year, with approximately ten to fifteen percent classified as aggressive or metastatic. These figures reinforce the reality that the market is small in absolute patient volume yet highly significant in clinical intensity, economic burden, and therapeutic complexity. The relatively limited incidence means that diagnostic precision, referral pathways, and specialist engagement become decisive factors in both patient outcomes and commercial execution.
The treatment standard similarly shapes strategic assumptions. Surgical resection remains the primary curative option for localized insulinoma, and for inoperable or malignant cases, medical management typically begins with diazoxide as first-line therapy, followed by somatostatin analogs or other interventions for refractory hypoglycemia. Yet a meaningful portion of the patient population does not achieve adequate disease control through existing protocols. Approximately four in ten patients are considered refractory to surgery and medical management including diazoxide, and an estimated 1,500 initially addressable malignant insulinoma patients exist in the United States alone. These numbers are central to planning, because they highlight both the urgency of expanding therapeutic options and the commercial reality that any successful innovation must navigate narrow patient subsets, specialized clinical workflows, and highly scrutinized value propositions.
Strategic positioning in this environment requires disciplined segmentation, realistic forecasting, and an understanding of how clinical evidence translates into adoption. Decision-makers must evaluate how new therapies will integrate into existing care pathways, whether they will reshape referral patterns, and how payers, providers, and research centers will interpret efficacy, safety, and cost-effectiveness. The presence of refractory subpopulations, combined with the rarity of the disease, also means that clinical development strategies and market access plans must be tightly synchronized. Delays, misalignments, or ambiguous evidence packages can materially affect timelines, pricing expectations, and the overall commercial trajectory of an intervention.
Infrastructure, End-User Architecture, and First-Mover Advantages
The delivery of insulinoma-related care is not uniformly distributed across healthcare systems. Instead, it is organized through a layered infrastructure of hospitals, specialty clinics, and diagnostic and research centers, each playing distinct roles in diagnosis, treatment, longitudinal management, and evidence generation. Hospitals continue to anchor procedural capabilities and acute management, while specialty clinics increasingly support complex case coordination and long-term monitoring. Diagnostic and research centers are becoming critical nodes for patient identification, biomarker exploration, trial enrollment, and multidisciplinary consultation.
This end-user architecture matters for strategic planning because it influences how products and services reach the market, how adoption is reinforced, and where commercial value is concentrated. Organizations seeking to enter or expand within this market must determine which care settings offer the most credible pathways to early uptake, which institutional partners can accelerate clinical education, and how reimbursement and procurement dynamics vary across settings. In rare disease markets, the speed and credibility of early clinical endorsement often determine downstream scale. First-mover advantages are therefore not simply about being early; they are about establishing durable relationships with the institutions that define standards of care, support physician decision-making, and validate new therapeutic approaches through real-world use and research activity.
The interplay between clinical concentration, infrastructure distribution, and evidence generation also shapes partnership strategy. Companies may need to align with specialty networks for trial recruitment, collaborate with diagnostic centers for patient identification, or engage hospital-based programs for procedural and translational research. In each case, the objective is to embed commercial initiatives within the operational logic of the care ecosystem rather than treating the market as a uniform endpoint. This approach improves forecasting reliability, reduces adoption friction, and strengthens the credibility of launch planning.
Worldwide Insulinoma Market
Why the 2026 Decision Cycle Demands Precision Intelligence
The 2026 business environment places exceptional pressure on strategic teams to make informed capital, pipeline, and market-entry decisions with limited room for error. In a specialized market like insulinoma, where growth is steady rather than explosive, differentiation depends on understanding structural drivers, anticipating clinical catalysts, and identifying where value is likely to accrue across treatment types, end-user settings, and regional ecosystems. Broad market summaries are insufficient for this task because they do not reveal how demand is distributed, how competitive concentration influences pricing and access, or how regulatory milestones may alter adoption timelines.
This is precisely the type of intelligence gap that our Worldwide Insulinoma Market research is designed to address. The study offers a granular, decision-oriented assessment of the market's historical baseline, forward trajectory, and operational architecture, while deliberately maintaining confidentiality around detailed segment-level figures and proprietary analytics. In practice, this means that executives can rely on the report as a framework for benchmarking assumptions, testing strategic scenarios, and aligning internal planning with market realities, while still being compelled to obtain the complete dataset and analytical models for precise execution.
The strategic value of this approach lies in precision without dilution. For R&D leaders, the report supports assessment of therapeutic positioning, development timelines, and clinical adoption risks. For commercial teams, it informs segmentation planning, channel prioritization, and launch sequencing. For corporate development and investment functions, it clarifies concentration dynamics, competitive exposure, and the likely shape of value creation across the forecast horizon. Rather than offering generic market commentary, the analysis connects epidemiological constraints, treatment standards, regulatory alignment, and infrastructure distribution into a coherent strategic map.
What the Report Delivers and How to Use It
The Worldwide Insulinoma Market report has been structured to function as a working intelligence asset rather than a static overview. It integrates historical performance context, forward-looking market projections, segmentation dynamics, competitive profiles, and industry catalyst tracking into a single decision-support framework. Readers will find detailed coverage of market size evolution from 2020 through the forecast window extending to 2032, alongside analysis of how treatment typologies, end-user configurations, and regional distributions influence commercial behavior and adoption patterns. The report also includes competitive profiling that goes beyond corporate descriptions, examining how developer strategy, trial design, regulatory alignment, and indication expansion shape competitive positioning within a concentrated market.
Importantly, the study emphasizes operational interpretation over raw enumeration. It examines how surgical, pharmacological, targeted, and peptide-based modalities interact within the current care paradigm, how specialized institutions influence early adoption and evidence accumulation, and how rare-disease dynamics shape pricing, reimbursement, and market access logic. This orientation enables users to translate macro-level trends into actionable planning assumptions, such as where to prioritize clinical engagement, how to sequence partnership activity, and which indicators should be monitored to anticipate shifts in competitive intensity or treatment standards.
Because the report is built for strategic application, it also supports scenario planning. Decision-makers can use the analysis to evaluate how changes in regulatory outcomes, trial readouts, or reimbursement environments may affect commercial timelines, market concentration, and relative positioning among incumbents and emerging entrants. In a market where key catalysts are unfolding within the 2026 to 2032 horizon, the ability to model alternative outcomes is a practical necessity rather than an academic exercise.
Conclusion: Strategic Certainty in a Specialized Market
The worldwide insulinoma market is not defined by scale alone, but by the precision with which organizations can interpret clinical need, regulatory evolution, competitive concentration, and infrastructure dynamics. The historical growth observed between 2020 and 2025, combined with the projected trajectory through 2032, confirms that this is a market where disciplined insight can create meaningful strategic advantage. For companies operating in endocrinology, oncology support, medical technology, or specialized care delivery, the ability to read segmentation behavior, anticipate catalyst impacts, and navigate concentrated competitive structures will increasingly differentiate successful strategies from reactive ones.
Our Worldwide Insulinoma Market research is designed to provide that advantage. It offers the analytical rigor, structural clarity, and market-specific intelligence required to make high-stakes decisions with greater confidence, while preserving the detailed quantitative and proprietary elements that underscore its value. For executives who need a complete, decision-ready intelligence foundation, we invite you to access the full report and obtain the comprehensive data, segmentation detail, and competitive analysis necessary to translate strategic vision into executable planning for 2026 and the years ahead.
Lumpectomy Market
For detailed analysis of this topic, please visit the official page: Worldwide Insulinoma Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: NBR Latex Market to Grow at 8.01% CAGR to $4,476M by 2032
By pmarketresearch, 2026-09-16
Navigating the Next Wave: Strategic Outlook for the Global NBR Latex Market (2026-2032)
The global Nitrile Butadiene Rubber (NBR) latex market is entering a decisive phase where demand resilience meets supply chain recalibration. As industries ranging from healthcare to advanced manufacturing continue to depend on nitrile-based solutions for their chemical resistance, durability, and safety profiles, the market has demonstrated a clear upward trajectory. Our latest Worldwide NBR Latex Market study maps this evolution across a base year of 2025 and projects forward through 2032, offering a decision-ready framework for executives, procurement leaders, and investors who must align capacity planning, sourcing strategies, and innovation roadmaps with structural market realities.
The historical record from 2020 through 2025 reveals a market that has absorbed significant volatility while maintaining a strong long-term growth impulse. Total industry revenue, measured in millions of USD, moved from approximately 2,410.5 in 2020 to 2,610.0 in 2025, with annual fluctuations reflecting the interplay of pandemic-era demand spikes, subsequent normalization, feedstock cost dynamics, and shifting end-user procurement patterns. Looking ahead, the forecast window from 2026 to 2032 indicates sustained expansion, with projected revenue climbing toward 2,885.0 in 2026 and reaching roughly 4,476.0 by 2032. This progression corresponds to a compound annual growth rate of 8.01 percent, a figure that underscores both the underlying strength of end-use consumption and the market's capacity to compound value across multiple cycles. For strategic planners, this growth path is not merely a headline statistic. It is a signal that the NBR latex landscape will reward organizations capable of anticipating regional supply shifts, grade-specific demand migration, and the accelerating push toward more sustainable production architectures.
Why This Study Matters for 2026 Decision-Making
Market intelligence is only as valuable as its capacity to reduce uncertainty in real operational contexts. The 2026 planning cycle presents a distinctive set of challenges: feedstock input costs remain sensitive to crude oil fluctuations and geopolitical conditions; regulatory frameworks in key jurisdictions are reshaping formulation priorities; and logistics disruptions have periodically tested the reliability of cross-border supply. In this environment, a robust market assessment must do more than track top-line growth. It must connect macro trends to actionable decisions about capacity allocation, grade portfolio optimization, supplier diversification, and sustainability positioning.
Our analysis is structured to help leadership teams answer the questions that directly affect margin performance and competitive posture. Which application segments are reinforcing steady demand, and where is growth being amplified by regulatory or substitution dynamics? How are grade distinctions between medical-grade and industrial-grade pathways shaping procurement requirements and pricing power? Where are the concentration patterns among leading manufacturers creating both partnership opportunities and supply vulnerability? By integrating historical performance with forward-looking indicators, the report equips stakeholders to stress-test assumptions, prioritize investments, and identify white spaces that align with their operational capabilities.
Scope and Structure of the Analysis
This study is designed as a practical navigation tool rather than a static data table. It brings together market sizing, segmentation logic, competitive profiling, and industry context into a coherent narrative that can be used across functions, from strategy and business development to supply chain and R&D. The analytical framework is organized around the dimensions that most directly influence commercial outcomes.
Segmentation Perspectives
- Regional distribution of market activity and the relative significance of major geographic zones, including Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa
- Application-oriented demand patterns across principal end-use categories such as medical gloves, industrial gloves, adhesives and sealants, and other applications
- Grade-level differentiation between medical-grade and industrial-grade NBR latex, including the implications for specification requirements, compliance, and end-customer expectations
Competitive Landscape and Producer Profiles
The report profiles a broad set of globally active producers and regional specialists whose strategies shape pricing, availability, and product development directions. These include major integrated and specialty players such as LG Chem, Zeon Corporation, ARLANXEO, Kumho Petrochemical, Synthomer, LANXESS, Apcotex Industries Limited, SIBUR, China Petroleum & Chemical Corporation (Sinopec), Nantex Industry Co., Ltd., JSR Corporation, Bangkok Synthetics Co., Ltd., and Nitriflex S.A. Rather than presenting a simple roster, the analysis examines how each organization's geographic footprint, capacity posture, grade focus, and innovation emphasis influences its role within the wider supply network.
Recent Developments Shaping Market Direction
Recent industry activity highlights a clear trend toward diversification of supply and the introduction of more sustainable product options. Synthomer has pursued bio-based NBR latex initiatives, including partnerships aimed at lowering carbon emissions for glove production and the launch of certified sustainable latex lines with reduced carbon footprints. In parallel, capacity expansion efforts continue to reshape regional supply balances, with new plant commissions adding volume in key Asian manufacturing hubs. These moves reflect a broader industry posture in which producers are investing not only in scale, but also in product differentiation and environmental performance.
Market Concentration and Strategic Implications
The competitive structure of the market remains moderately concentrated, with a meaningful share of activity held by leading producers. This concentration matters because it affects negotiating leverage, supply reliability, and the speed at which new grades or process improvements can propagate through the value chain. For buyers, it informs supplier qualification strategies and contingency planning. For manufacturers, it highlights the importance of brand positioning, application-specific technical support, and regional service capabilities as differentiators in a market where scale alone does not guarantee preference.
Industry Dynamics Shaping the 2026-2032 Outlook
No market analysis is complete without attention to the forces that can accelerate, delay, or redirect growth. In the NBR latex sector, several overlapping dynamics are particularly relevant for near-term planning and longer-range scenario building.
Worldwide Nitrile Butadiene Rubber (NBR) Latex Market
Feedstock Cost and Supply Sensitivity
Butadiene and acrylonitrile are core inputs in NBR latex production, and their cost behavior has a direct bearing on manufacturing economics. During 2025 and into 2026, feedstock conditions have been influenced by crude oil-linked pricing and periods of supply tightness tied to broader geopolitical factors. For producers, this translates into cost volatility that must be managed through formulation efficiency, procurement timing, and, where possible, grade mix adjustments. For downstream users, it reinforces the importance of forward contracting, multi-source sourcing, and specification flexibility where performance requirements permit.
Regulatory Pressure and Formulation Evolution
Regulatory expectations continue to shape product development priorities, particularly in Europe, where REACH-related considerations are encouraging demand for lower-VOC and more sustainable NBR latex grades. At the same time, medical and industrial end-users are increasingly attentive to documented compliance, traceability, and environmental attributes. These pressures are not simply constraints; they are becoming selection criteria that can differentiate suppliers with robust technical and sustainability portfolios from those relying solely on price competition.
Logistics, Trade Policy, and Regional Availability
Physical availability remains a critical operational theme. Shipping route disruptions and regional supply concerns have at times affected the reliability of NBR latex deliveries, with repercussions for glove manufacturers and industrial converters dependent on timely input flows. In parallel, trade policy developments, including tariff adjustments affecting certain imports, have introduced additional complexity into cross-border procurement. These factors increase the value of visibility into route-level risk, inventory buffering strategies, and the geographic alignment of supply with demand centers.
Strategic Takeaways for Stakeholders
Taken together, the 2026-2032 outlook points to a market where growth is real but conditional on operational agility. Organizations that can read the intersection of demand structure, feedstock exposure, regulatory direction, and competitive concentration will be best positioned to convert market expansion into durable advantage. Several strategic themes emerge as particularly important.
Nitrile Rubber (NBR) Market
For Producers and Material Suppliers
- Grade specialization and application-specific technical support are likely to become stronger differentiators as buyers seek reliability and performance assurance alongside cost efficiency
- Sustainable and lower-carbon product options are moving from optional innovation to a competitive expectation in selected segments, making portfolio breadth increasingly relevant
- Capacity decisions should be evaluated not only against volume forecasts, but also against regional demand shifts, feedstock access, and logistics resilience
For Convertors, Glove Manufacturers, and Industrial Users
- Supplier qualification strategies should account for concentration risk, geographic exposure, and the ability to maintain continuity during transport or policy disruptions
- Specification management offers an important lever: where performance requirements allow, grade and source flexibility can reduce exposure to cost and availability shocks
- Sustainability attributes and compliance documentation are increasingly part of purchasing decisions, especially in regulated and customer-facing applications
For Investors and Strategic Partners
- Growth visibility is strongest where end-use demand is supported by medical, industrial, and specialty adhesive and sealant consumption patterns, but realization depends on supply-side execution
- Competitive positioning will increasingly favor players that can combine scale with differentiated grades, regional service depth, and credible sustainability narratives
- M&A, partnerships, and capacity collaboration may be especially relevant where feedstock integration, bio-based development, or regional supply balancing can create durable cost or availability advantages
How to Use This Study
This report is intended to support concrete decision-making processes rather than abstract market observation. It can serve as a reference for annual planning cycles, sourcing reviews, capacity expansion evaluations, and competitive benchmarking exercises. By linking historical performance to forward indicators and embedding both producer-level and industry-level context, the study provides a common analytical language for cross-functional teams. The goal is to help decision-makers distinguish between temporary fluctuations and structural shifts, and to prioritize actions that are robust across multiple plausible scenarios.
The global NBR latex market is on a measurable growth path, but the value of that trajectory will be captured by organizations that treat market intelligence as an operational input. With sustained demand across medical and industrial segments, ongoing feedstock and logistics complexity, and a competitive field that rewards both scale and specialization, 2026 represents a pivotal year for setting strategy. Our full Worldwide NBR Late latex Market report extends this foundation with detailed segmentation analysis, comprehensive company profiles, development timelines, and scenario-relevant context, enabling teams to move from insight to execution with greater confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Nitrile Butadiene Rubber (NBR) Latex Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Digital Dermatoscope Market Hits $1.16B in 2025, Projects 9.2% CAGR to 2032
By pmarketresearch, 2026-09-16
Unlocking Market Intelligence: Strategic Insights into the Worldwide Digital Dermatoscope Market
The global healthcare technology landscape is undergoing a profound transformation, driven by an aging population, rising prevalence of skin cancer, and the rapid integration of artificial intelligence into diagnostic workflows. Within this ecosystem, digital dermatoscopy stands out as a critical frontier, bridging the gap between traditional clinical examination and advanced digital health solutions. As we move deeper into the mid-2020s, understanding the trajectory of this market is no longer optional for stakeholders; it is a strategic imperative.
This article serves as a strategic preview to our latest comprehensive study, the Worldwide Digital Dermatoscope Market Research. Our objective is to outline the macroeconomic forces shaping the industry, highlight the competitive dynamics at play, and demonstrate why access to granular, data-backed intelligence is essential for informed decision-making in 2026 and beyond. True mastery of this landscape requires a compass grounded in precise data, which our full report provides in detail.
Market Trajectory and Growth Dynamics
The digital dermatoscope sector has demonstrated remarkable resilience and expansion over the past half-decade. Our historical analysis from 2020 through 2025 reveals a consistent upward trend in market valuation, reflecting the accelerated adoption of digital imaging tools in clinical settings. Building on this momentum, the forecast period from 2026 to 2032 projects sustained growth, with the market expected to reach new valuation milestones by the end of the decade.
Worldwide Digital Dermatoscope Market
Central to our forecast is a robust Compound Annual Growth Rate (CAGR), indicating that the industry will continue to expand at a pace well above many mature medical device categories. This growth is underpinned by several structural drivers: the increasing demand for non-invasive diagnostic procedures, the rollout of telemedicine infrastructure that relies on high-quality digital imaging, and the growing homogenization of healthcare standards across emerging markets. However, growth is not uniform across all vectors, and understanding where value is being created requires a nuanced view of product types, end-user segments, and geographic penetration.
Our full analysis dissects these trends, offering stakeholders a clear view of the total addressable market. The data indicates that while the overall market size is expanding significantly, the distribution of revenue across different segments varies considerably based on regulatory environments, reimbursement policies, and technological maturity. For investors and product leaders, identifying the high-growth pockets within this broader expansion is key to capitalizing on the opportunity.
Dermatoscope Market
Segmentation and Value Chains
To navigate this market effectively, one must look beyond aggregate numbers. The Worldwide Digital Dermatoscope Market is segmented across multiple dimensions, each presenting distinct strategic considerations. On the product front, the ecosystem is divided between portable handheld devices and integrated imaging systems. Each category serves different clinical needs, price points, and workflow requirements. Handheld units often appeal to practitioners seeking flexibility and ease of deployment, while integrated systems are favored by large-scale clinics and hospitals requiring comprehensive data management and total body mapping capabilities.
End-user segmentation further illuminates where demand is concentrated. Dermatology clinics represent a primary hub for adoption, driven by the need for efficient lesion tracking and patient monitoring. Hospitals and academic research institutes also form significant pillars of demand, often driven by complex case management and the integration of dermoscopy into broader diagnostic protocols. Understanding the specific revenue contributions and growth rates within these segments allows companies to tailor their go-to-market strategies with precision.
Regionally, the market presents a diverse landscape. North America and Europe have historically commanded the largest shares of revenue, supported by well-established healthcare reimbursement frameworks and high awareness of skin cancer screening. Meanwhile, the Asia Pacific region is emerging as a critical growth engine, fueled by expanding healthcare access and increasing investment in medical technology infrastructure. Latin America and the Middle East and Africa, while currently smaller in absolute terms, offer untapped potential as digital health initiatives gain traction. Our report provides a detailed breakdown of these regional dynamics, enabling stakeholders to prioritize markets that align with their risk appetite and strategic goals.
Competitive Landscape and Innovation Waves
The competitive environment in the digital dermatoscope market is characterized by a mix of established medical device manufacturers and specialized technology firms. Market concentration is notable, with a core group of players holding a significant portion of industry revenue. Understanding the positioning, technological differentiators, and strategic moves of these key players is vital for benchmarking and identifying partnership or acquisition opportunities.
Leading manufacturers such as Heine Optotechnik and DermLite continue to drive product innovation, focusing on enhanced imaging quality, user ergonomics, and connectivity features. Heine Optotechnik's DELTA series, for instance, has been widely recognized for its precision and AI integration capabilities aimed at melanoma detection. Similarly, DermLite has maintained a strong presence with its DL series, leveraging polarized and non-polarized light modes alongside robust connectivity solutions that support teledermatology workflows.
Complementing these device manufacturers are companies offering sophisticated software and integrated platforms. FotoFinder Systems has carved a significant niche with its Moleanalyzer and Medicam offerings, emphasizing AI-based lesion analysis and total body mapping. Recent developments, such as the launch of enhanced AI algorithms, underscore the industry's shift toward data-driven diagnostics. Canfield Scientific also contributes to this landscape with its DermaGraph and IntelliStudio systems, integrated with vision software for comprehensive dermatological imaging and tracking. Smaller yet agile players like Dinolite and AnMo Electronics Corporation provide portable and wireless solutions, often targeting cost-sensitive segments or specific clinical use cases with features like high-megapixel sensors and adjustable magnification.
The pace of innovation is rapid, and recent activity illustrates the intensity of competition. Product launches, certification updates, and strategic appearances at major medical conferences are frequent signals of market evolution. These events often signal shifts in regulatory compliance, feature sets, or market entry strategies. Our full report catalogs these developments, providing a timeline of key milestones that stakeholders can use to anticipate competitive moves and align their own roadmaps.
Regulatory, Reimbursement, and Operational Dynamics
Beyond technology and competition, the market is heavily influenced by regulatory frameworks and reimbursement policies. Compliance with medical electrical equipment safety standards, such as IEC 60601-1, is a non-negotiable requirement for manufacturers seeking to operate in major healthcare markets. Adherence to these standards not only ensures patient protection but also serves as a barrier to entry for less established players, consolidating the position of incumbents.
Reimbursement dynamics further shape market accessibility. In the United States, for example, specific CPT codes cover dermoscopy procedures using digital devices in outpatient settings. The availability and clarity of such codes directly impact the adoption rate of digital dermoscopes, as they influence the economic viability for healthcare providers. Changes in reimbursement landscapes can accelerate or decelerate demand, making it essential for stakeholders to monitor policy updates closely.
On the operational side, manufacturing costs remain a critical consideration. Medical-grade optics and LED components constitute a substantial portion of production expenses. Fluctuations in the availability or pricing of these components can affect margins and pricing strategies. Companies with strong supply chain management and vertical integration capabilities are better positioned to navigate these cost pressures while maintaining competitive pricing.
Strategic Imperatives for 2026
As we look toward 2026, several strategic imperatives emerge for participants in the digital dermatoscope market. First, differentiation through technology remains paramount. The integration of AI algorithms for lesion analysis, enhanced connectivity for telehealth, and ergonomic improvements are no longer optional features; they are baseline expectations. Companies that can innovate faster and more effectively will capture greater market share.
Second, market expansion requires a targeted approach. Given the varying maturity levels across regions and segments, a one-size-fits-all strategy is unlikely to succeed. Stakeholders must assess local regulatory requirements, reimbursement environments, and clinical workflows to tailor their offerings. In emerging markets, affordability and ease of use may take precedence, while in established markets, advanced features and integration with existing health IT systems may drive purchasing decisions.
Third, partnerships and ecosystem building are increasingly important. Collaboration with academic institutions, dermatology associations, and technology providers can accelerate R&D, validate clinical efficacy, and expand distribution networks. Additionally, as data becomes central to dermatological care, companies must address data privacy, security, and interoperability concerns to build trust with healthcare providers and patients.
Conclusion
The Worldwide Digital Dermatoscope Market represents a dynamic and growing opportunity at the intersection of healthcare, technology, and patient care. The trajectory from 2020 through 2032 points to sustained expansion, driven by technological innovation, demographic shifts, and evolving clinical standards. However, capturing value in this market requires more than a surface-level understanding. It demands deep, data-driven insights into segmentation, competition, regulatory frameworks, and regional nuances.
Our comprehensive research study provides exactly that depth. From granular revenue splits across product types, end users, and regions to detailed competitor profiles and recent industry developments, the report offers a complete intelligence package for strategic planning. It enables stakeholders to benchmark performance, identify high-growth opportunities, assess competitive threats, and formulate robust market entry or expansion strategies.
For investors, manufacturers, and healthcare providers aiming to make informed decisions in 2026 and beyond, the full report is an indispensable resource. It transforms complex market data into actionable intelligence, empowering you to navigate the digital dermatoscope landscape with confidence. We invite you to explore the complete analysis and unlock the full strategic value of this evolving market.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Dermatoscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Global Phenolic Molding Compound Market to Hit $3,128.18M by 2032, CAGR 4.85%
By pmarketresearch, 2026-09-16
Navigating the Future of the Global Phenolic Molding Compound Market: Strategic Insights for 2026 and Beyond
The phenolic molding compound (PMC) industry stands at a critical inflection point. As global manufacturing ecosystems oscillate between post-pandemic normalization, supply chain restructuring, and accelerating electrification, decision-makers across automotive, electrical, and industrial sectors require more than surface-level trend summaries. They need granular, forward-looking intelligence calibrated for execution. Our newly released Worldwide Phenolic Molding Compound Market study delivers exactly that: a rigorous, data-driven blueprint for navigating the 2026-2032 horizon.
This article outlines the strategic architecture of the report, interprets the macro trajectory shaping the industry, and demonstrates how procurement leaders, product developers, and competitive intelligence teams can leverage the findings to secure operational advantage in the coming years.
Market Trajectory: Decoding the 2026-2032 Growth Arc
The global PMC market has demonstrated remarkable resilience through a volatile five-year cycle. Tracking historical performance from 2020 through the 2025 base year reveals a compound revenue stream that weathered raw material shocks, geopolitical trade friction, and shifting end-use demand. The overall market expanded from approximately 1,810.45 million USD in 2020 to a 2025 valuation of 2,245.5 million USD. While 2024 registered a temporary contraction to 2,082.15 million USD—a reflection of inventory corrections and regional demand recalibration—the subsequent rebound underscores the sector's structural durability and the latent pull from high-growth downstream applications.
Looking ahead, our forecast model projects the market to reach 2,430.68 million USD in 2026, accelerating through the end of the decade to touch 3,128.18 million USD by 2032. This trajectory translates to a forecasted CAGR of 4.85 percent across the 2026-2032 period. For strategic planners, this growth rate is not merely a headline figure; it signals a maturing but still expanding addressable space where incremental gains will be captured by firms that align product portfolios with regional price dynamics, regulatory shifts, and application-specific performance requirements.
Phenolic Resins Market
Crucially, the forecast accounts for divergent regional fundamentals. Raw material pricing volatility, exemplified by phenol markets in Q1 2026, illustrates why a uniform global strategy is insufficient. In Northeast Asia, phenol prices climbed to 1.01 USD/KG in March 2026, reflecting an 8.6 percent upward move from December driven by firm demand from phenolic resin manufacturing and rising cumene feedstock costs. Europe presents a contrasting picture: prices settled at 1.00 USD/KG, dipping 3.8 percent amid softening resin-sector demand and competitive Asian imports. North America registered 1.18 USD/KG, with a modest 0.8 percent decline against a backdrop of adequate local production and slightly weak resin demand. These price divergences directly influence margin structures, sourcing strategies, and regional capacity allocation—variables our report dissects in depth.
Report Architecture: What Decision-Makers Will Find Inside
The Worldwide Phenolic Molding Compound Market study is engineered for execution. Rather than offering static snapshots, the report maps the value chain from raw material inputs through compounding, molding processes, and end-use deployment. Every section is designed to answer the questions that keep strategy and operations leaders awake at night: where will volume concentrate, which product architectures will command pricing power, and how should organizations position against intensifying regional competition.
Granular Segmentation Analysis
The report deconstructs the market across multiple dimensions, enabling readers to isolate the sub-segments that align with their strategic mandates. A thorough type-level evaluation contrasts Novolac and Resol phenolic resin architectures, examining how their distinct curing behaviors, thermal profiles, and cost structures position them across compression, transfer, and injection molding workflows. Application-level analysis traces demand drivers across automotive, electrical and electronics, industrial components, aerospace and defense, and other emerging verticals. Each application segment is examined through the lens of performance thresholds, certification requirements, and substitution risk, providing a clear view of where growth will materialize and why.
Worldwide Phenolic Molding Compound Market
Regional Supply-Demand Equilibrium
Regional dynamics receive dedicated treatment, recognizing that PMC consumption is fundamentally shaped by local manufacturing footprints, logistics constraints, and raw material accessibility. The analysis maps production capacity distribution, evaluates regional pricing pressure points, and identifies how trade flows and localized resin demand are reshaping competitive positioning. Readers will gain a clear understanding of which regions function as volume engines, which are transitioning toward higher-value formulations, and where supply gaps may create tactical opportunities.
Competitive Landscape: Who Holds the Field and How the Board Is Shifting
Market concentration in the global PMC sector remains moderate, with the top three players collectively commanding approximately 24.15 percent of revenue and the top five holding 38.6 percent. This fragmented-but-consolidating structure creates both defensive moats and offensive openings. The report profiles the firms defining the competitive terrain, analyzing their geographic reach, technical differentiators, and strategic maneuvers.
- Sumitomo Bakelite Co., Ltd. (Tokyo, Japan) maintains a globally integrated footprint spanning production sites in Shizuoka, Nantong, North America, Belgium, and Singapore. Its portfolio emphasizes glass-fiber-reinforced and filler-modified phenolic compounds engineered for weight reduction, cost efficiency, and design flexibility. In March 2026, the company launched a new series of high-adhesion phenolic resins designed for diverse material interfaces, broadening its formulation capabilities for advanced molding applications. This followed a 2024 capacity expansion in Nantong, China, which added significant volume to its regional supply base.
- PLENCO (Plastics Engineering Company), headquartered in Sheboygan, Wisconsin, USA, delivers both novolac and resol phenolic resins alongside tailored molding compounds. Its value proposition centers on dimensional stability, electrical insulation, and heat resistance, serving industrial customers across compression, transfer, and injection molding processes.
- Bakelite Synthetics (Bakelite), with multiple US sites and global reach, emphasizes high-quality thermoset solutions for consumer goods, electrical, and industrial sectors. Its strategy hinges on consistent quality assurance and broad application coverage across mature and growing verticals.
- Chang Chun Plastics Co., Ltd. (Taiwan) manufactures the LONGLITE brand of heat-hardening phenolic molding compounds, formulated to meet customer-specific requirements in electrical, automotive, and industrial applications. Its regional strength in Asia positions it to capture demand tied to localized supply chain development.
- Resinoid Engineering Corporation (USA) specializes in phenolic compound raw goods and custom compounding, with a particular emphasis on high-temperature materials rated for continuous use above 400°F. Its aftermarket automotive focus makes it a notable player in performance-critical niche applications.
- Shengquan Group (China) ranks among the largest phenolic resin manufacturers globally, supplying resins for molding compounds to both domestic and international enterprises. Its scale and integrated supply chain provide a cost-advantaged base for regional and export markets.
- Kaihua Ruida Plastic-Tech Co., Ltd. (Zhejiang, China) produces UL-approved phenolic molding compounds and Bakelite powders, including the PF2D1-9600J series, engineered for heat resistance and dimensional stability across appliance, construction, and automotive sectors.
The report does not stop at profiles. It evaluates how recent capacity investments, product launches, and regional pricing pressures are reshaping share dynamics. Readers will understand which players are expanding into high-performance formulations, which are leveraging cost leadership in core segments, and where consolidation or partnerships may alter the competitive hierarchy over the forecast period.
Industry Dynamics: Raw Material Pressure, Regulatory Anchors, and Demand Realignment
No strategic assessment of the PMC market is complete without addressing the forces that constrain or enable growth. Raw material economics remain the most immediate variable. As noted, phenol pricing divergence across Northeast Asia, Europe, and North America in early 2026 illustrates how regional feedstock costs and import competition directly influence compounding margins. The report integrates these pricing signals into forward-looking cost scenarios, helping procurement teams anticipate squeeze points and evaluate hedging, dual-sourcing, or formulation-adaptation strategies.
Regulatory and certification frameworks further shape market access, particularly in electrical and electronics applications. UL certification remains active for a wide array of phenolic molding compounds supplied as pellets, covering critical performance metrics such as flame class, hot wire ignition (HWI), high current arc ignition (HAI), and relative thermal index (RTI). Compliance with these standards is not optional; it is a gating requirement for market entry in safety-sensitive segments. Our analysis maps how certification requirements influence product development timelines, testing costs, and competitive positioning, enabling firms to align R&D investment with the compliance pathways that matter most to their target customers.
Beyond inputs and regulation, demand-side realignment is accelerating. Automotive electrification, lightweighting mandates, and the continued migration toward higher-efficiency electrical components are shifting the composition of PMC consumption. At the same time, industrial and aerospace applications continue to prize the thermal stability, arc resistance, and mechanical integrity that phenolic architectures deliver. The report examines how these demand vectors interact with regional supply capacity, helping readers anticipate which application segments will see tightening supply, which will benefit from formulation innovation, and where substitution risk warrants proactive portfolio planning.
Strategic Value for 2026 Decision-Making
The 2026-2032 window is not a period for passive observation. It is a window in which capacity commitments, formulation roadmaps, and sourcing architectures will determine which organizations capture margin and which concede share. Our study is built to convert market complexity into actionable clarity.
- For procurement and supply chain leaders, the report provides the regional price context and supply-concentration data needed to negotiate from an informed position, evaluate supplier risk, and structure resilient sourcing networks amid divergent raw material trends.
- For product development and engineering teams, the segmentation analysis highlights where novolac versus resol architectures, reinforcement strategies, and certification pathways create differentiation opportunities—and where performance thresholds are becoming table stakes.
- For competitive intelligence and corporate strategy functions, the firm-level profiles and concentration metrics reveal who is expanding, who is innovating, and where acquisition, partnership, or capacity investment may shift the balance of power.
- For executive planning, the macro trajectory—anchored in rigorous historical data and a transparent 2026-2032 forecast—offers a defensible baseline for capital allocation, market-entry evaluation, and long-range revenue modeling.
Importantly, the report is structured to support scenario planning rather than rigid forecasting. Market conditions will evolve as feedstock costs fluctuate, regulatory standards tighten, and end-use demand shifts with macroeconomic cycles. By grounding strategy in a detailed, evidence-based view of the market's architecture, organizations can adjust with confidence rather than react under pressure.
Accessing the Full Intelligence Package
The Worldwide Phenolic Molding Compound Market study goes far beyond the macro trajectory and competitive overview outlined here. It delivers detailed segmentation assessments, regional supply-demand equilibria, firm-level strategic evaluations, raw material cost scenarios, and certification-impact analysis—all calibrated to support decisive action in 2026 and throughout the 2032 horizon. Core quantitative breakdowns, sub-segment growth rates, and granular regional revenue splits are integrated into the complete report, enabling readers to model outcomes specific to their portfolios and geographies.
Organizations that treat this market as a single homogeneous block will miss the nuanced opportunities hidden in type-specific demand, regional pricing divergence, and application-level performance requirements. The firms that thrive will be those that combine technical precision with strategic foresight. This report is designed to supply both.
To access the full dataset, segmentation matrices, competitive deep dives, and forward-looking scenario analysis, request the complete Worldwide Phenolic Molding Compound Market research. The full intelligence package is available through our research portal, where you can review the complete forecast model, examine detailed firm profiles, and align the findings directly with your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Phenolic Molding Compound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Liquid Cooling Fast Connection Market Hits $1.24B in 2025, Forecast 18.25% CAGR to $4.01B by 2032
By pmarketresearch, 2026-09-16
Powering the Liquid Cooling Revolution: Strategic Intelligence for the Fast Connection Solutions Market
The thermal management landscape is undergoing a structural transformation. As artificial intelligence workloads intensify and data center power densities surge, the industry's reliance on air cooling has reached its physical and economic limits. Direct liquid cooling (DLC) and immersion cooling have transitioned from niche alternatives to essential infrastructure, driving unprecedented demand for reliable, high-performance fluid transfer components. At the heart of this shift lies the fast connection solutions ecosystem, a critical enabler of leak-free, high-flow, and rapid deployment cooling architectures.
PW Consulting's latest worldwide market research on Fast Connection Solutions for Liquid Cooling Systems offers a comprehensive, data-driven lens into this rapidly expanding sector. This article outlines the strategic imperatives shaping the 2026 decision-making environment, contextualizes the macroeconomic trajectory of the market, and previews the analytical depth available in the full report. For executives, engineers, and investors navigating the thermal infrastructure value chain, understanding the connective tissue of liquid cooling is no longer optional—it is a competitive necessity.
The Macro Trajectory: A Market in Hypergrowth
The financial signals from the past half-decade tell a clear story of acceleration. Valued at approximately 585.3 million USD in 2020, the global fast connection solutions market for liquid cooling systems has expanded consistently, closing 2025 at an estimated 1,241.18 million USD. The forward-looking projection is equally compelling: revenues are expected to surpass the 1,498 million USD threshold in 2026 and climb steadily toward 4,012.79 million USD by 2032. This translates to a compound annual growth rate of 18.25 percent throughout the 2026–2032 forecast horizon, placing the sector among the fastest-growing subsegments within the broader thermal management and fluid handling industries.
Worldwide Liquid Cooling Couplings Market
Such sustained expansion is not merely cyclical. It is fundamentally anchored in the architectural redesign of computing and energy infrastructure. As hyperscale operators, colocation providers, and industrial facilities migrate toward high-density thermal solutions, the requirement for quick disconnects, blind-mate connectors, and push-to-connect fittings has evolved from a maintenance convenience to a core design specification. The market's trajectory reflects a structural reordering of priorities: downtime minimization, pressure-drop optimization, coolant purity, and interoperability now dictate component selection as much as upfront cost.
Technology Architectures and Segment Dynamics
The market's growth is distributed across three primary connection architectures, each addressing distinct operational requirements. Non-spill quick disconnects dominate the volume landscape, engineered to maintain fluid integrity during mating and unmating cycles—a non-negotiable feature in live data center environments where coolant leaks can trigger immediate operational shutdowns. Blind-mate connectors address the need for automated, alignment-tolerant connections in high-density rack deployments, while push-to-connect fittings serve applications prioritizing rapid manual installation and serviceability.
Material science continues to shape segment performance. Metallic solutions, particularly those fabricated from stainless steel, aluminum, and brass, maintain a dominant position due to their structural strength, thermal resilience, and compatibility with high-pressure cooling loops. Simultaneously, polymer-based valve and piping architectures—leveraging materials such as PVDF, PP-H, and PE100—are gaining traction for their ability to reduce weight, optimize flow characteristics, and deliver leak-tight performance in precision cooling circuits. This dual-material evolution reflects a broader industry trend: component selection is increasingly driven by application-specific thermal loads, coolant chemistry, and facility layout constraints rather than one-size-fits-all specifications.
Geographic Distribution and Application Diversification
Demand is not evenly distributed across the globe, nor is it concentrated in a single end-use vertical. The market exhibits a clear geographic weighting that mirrors regional data center build-out, semiconductor fab expansion, and electric vehicle infrastructure deployment. Supply chains, manufacturing footprints, and local compliance environments further differentiate regional demand patterns, creating both localized opportunities and cross-border procurement considerations for multinational operators.
On the application side, data centers and high-performance computing environments represent the most substantial demand driver, reflecting the direct correlation between AI accelerator density and liquid cooling adoption. Electric vehicle charging and energy storage infrastructure contributes a meaningful secondary demand stream, particularly where rapid coolant routing and field-serviceability are prioritized. Semiconductor manufacturing and medical/industrial equipment round out the application portfolio, each introducing specialized requirements around cleanliness, thermal stability, and connection reliability. The interplay between these verticals creates a diversified demand base that insulates the market from single-sector volatility while simultaneously raising the bar for component standardization.
Porter's Five Forces and Competitive Intensity
The competitive structure of the fast connection solutions market reflects a moderately concentrated landscape with room for both established incumbents and specialized challengers. Top-tier players collectively account for a substantial share of revenue, underscoring the importance of engineering reputation, certification portfolios, and long-term supply agreements in securing anchor contracts. At the same time, the fifth and sixth forces—substitute threats and new entrant potential—remain active. Standardization initiatives, modular cooling designs, and cross-vendor interoperability programs are gradually lowering switching costs, pressuring suppliers to compete on total cost of ownership, flow efficiency, and integration support rather than brand loyalty alone.
Bargaining power varies across the value chain. Large data center operators and hyperscale buyers wield considerable leverage in specifying connection standards and demanding compliance with open frameworks, while mid-tier integrators and facility contractors often rely on supplier-led engineering guidance to navigate fluid dynamics, pressure ratings, and material compatibility. Supplier power is moderated by a healthy pipeline of qualified manufacturers across North America, Europe, and Asia Pacific, though lead-time reliability, quality assurance, and post-installation support remain critical differentiators. The threat of substitutes is muted by the physical specificity of liquid cooling loops, yet the rise of polymer-based valve assemblies and hybrid metal-polymer designs keeps the innovation frontier active.
Competitive Landscape: Leaders and Strategic Moves
The market features a cohort of well-established industrial coupling manufacturers and thermal management specialists, each carving distinct positioning within the liquid cooling ecosystem. CPC (Colder Products Company) continues to advance its Everis series quick disconnect couplings, including blind-mate and high-flow variants engineered for electronics and data center thermal management, backed by rigorous reliability testing protocols. Parker Hannifin's Quick Coupling Division emphasizes dripless, non-spill performance under pressure, targeting server and rack cooling applications where thermal loads and uptime expectations are exceptionally high.
CEJN has strengthened its footprint in data center CDU applications by supplying high-flow, low-pressure-drop quick connect couplings, including OCP-compliant series developed alongside industry leaders to enable blind-mate and interchangeable deployment scenarios. Danfoss, through its Hansen thermal management line, focuses on optimized flow paths that reduce pressure drop while maintaining robust thermal control for electronics and liquid-cooled infrastructure. Stäubli brings clean-break, quick and dry disconnect solutions to both industrial and data center environments, with recent product introductions targeting compact liquid-cooled optical architectures where space constraints and high-temperature performance intersect.
Amphenol Industrial Operations supports a broad portfolio of liquid cooling quick disconnect connectors spanning blind-mate, quick-connect, and high-flow architectures, serving data centers, EV infrastructure, and energy storage systems. Gates Corporation advances full-flow quick disconnect couplings tailored for direct-to-chip liquid cooling, prioritizing secure and simple connections compatible with existing facility infrastructure. Specialty Manufacturing Co. contributes custom and standard thermal management quick disconnects, including the Universal Quick Disconnect series, with an emphasis on reliability in electronics cooling contexts. TITAN Fluid has emerged as a notable player offering stainless steel quick disconnect couplings that align with OCP and NVIDIA specifications, targeting zero-downtime connection requirements in high-performance data centers. Motivair, operating under Schneider Electric, supplies Everis quick connects and Dynamic Cold Plates designed for seamless water transfer in direct-to-chip cooling architectures.
Recent product and partnership activity underscores how actively this competitive field is evolving. In early 2026, GF and Rittal announced a full-scope polymer cooling infrastructure solution, featuring a patented dual-ball valve in PVDF designed for direct-to-chip liquid cooling with optimized flow paths and leak-tight operation. Around the same period, Stäubli unveiled a compact quick disconnect variant aimed at liquid-cooled optical modules during a major industry keynote, highlighting the push toward miniaturization in high-density photonic cooling. Earlier initiatives included trade show showcases and technical publications addressing leakage-free connections for battery energy storage systems, low-pressure-loss coupling demonstrations for semiconductor and data center cooling, and engineering guidance on reducing pressure drops to improve thermal management energy efficiency. These moves illustrate a market where product differentiation, standards alignment, and application-specific validation are accelerating simultaneously.
Regulatory and Standards-Driven Demand Catalysts
External mandates and industry guidelines are acting as powerful adoption accelerants. Updated thermal guidelines for data processing environments and dedicated liquid cooling recommendations have codified the viability of higher supply temperatures and energy-efficient loop designs, reinforcing the case for liquid cooling in high-density server environments. Complementary standards defining data center efficiency metrics place cooling system performance under continuous scrutiny, while regional energy efficiency mandates increasingly favor infrastructure choices that support lower power usage effectiveness targets. In parallel, the broader shift toward direct liquid cooling and immersion cooling is being driven by AI and HPC power density increases, with documented energy savings potential relative to traditional air cooling and the ability to support ultra-low facility efficiency ratios. These dynamics do not merely influence procurement preferences; they reshape engineering specifications, architectural planning, and capital allocation timelines across the digital infrastructure sector.
Worldwide Fast Connection Solutions for Liquid Cooling System Market
What the Full Report Delivers
The PW Consulting Worldwide Fast Connection Solutions for Liquid Cooling System Market study is designed to convert this complex landscape into actionable intelligence. Beyond the headline growth trajectory, the report deconstructs historical performance, forecast pathways, and the operational variables that will determine market outcomes through 2032. It provides a structured assessment of connection architecture demand, end-use application priorities, and regional demand weighting, while mapping the strategic behavior of leading manufacturers and emerging participants.
Practitioners will find detailed analysis of product development directions, materials and flow-optimization trends, and the regulatory and standards environment shaping specification requirements. The research also evaluates competitive positioning, partnership activity, and the practical implications of interoperability frameworks for supply chain planning and product selection. For organizations evaluating market entry, capacity expansion, component standardization, or supplier negotiation strategy, the report offers a decision-ready framework that connects market-level signals with segment-level execution considerations.
Strategic Takeaways for 2026 Decision-Makers
As liquid cooling transitions from specialized deployment to mainstream infrastructure, fast connection solutions have become a defining component of thermal reliability, serviceability, and system efficiency. The market's growth path reflects more than rising compute demand; it signals a fundamental rethinking of how facilities are designed, maintained, and scaled. Decision-makers who align their product roadmaps, procurement standards, and partnership strategies with this evolving reality will be better positioned to capture value in a market where performance, compliance, and interoperability increasingly determine competitive outcomes.
To obtain the full dataset, granular segmentation analysis, forecast breakdowns, and complete competitive profiles, we invite you to explore the complete PW Consulting market report. The detailed intelligence contained within provides the precision required to translate macro trends into executable strategy across engineering, commercial, and investment functions.
For detailed analysis of this topic, please visit the official page: Worldwide Fast Connection Solutions for Liquid Cooling System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com